
Can you finance a car with a 500 credit score, or will lenders stop at the number? Learning how to finance a car with a 500 credit score starts with understanding that your score can affect the terms you’re offered, but it doesn’t tell the whole story. Lenders may also review your income, employment history, existing debt, down payment, and the vehicle you want to buy.
It’s understandable to feel unsure about where to start. Loan offers can be hard to compare, and a monthly payment doesn’t show the full cost of borrowing. Before applying, set a budget and decide which loan details you’ll compare so you can judge whether an offer fits your finances.
This guide explains what lenders may consider beyond your credit score, how to compare financing routes using consistent terms, and what documents and questions to prepare before visiting a dealership. If you’re shopping in Fullerton, dealership financing and a trade-in valuation may also be part of your planning. The goal is to make a considered car-buying decision, not a rushed one.
Key Takeaways
- A 500 credit score doesn’t automatically determine whether you’ll be approved; lenders may weigh your broader financial picture and loan details.
- Learn how to finance a car with a 500 credit score by comparing APR, loan term, amount financed, fees, and total repayment across options.
- Prepare for an application by reviewing your credit reports, setting a realistic payment budget, and gathering documents that support your income and obligations.
- Compare dealership financing with other application routes, and consider how a trade-in valuation could factor into your purchase plan.
- Explore used-car options and financing in Fullerton with a clear list of questions to ask before deciding.
Can You Finance a Car with a 500 Credit Score? Start with Realistic Expectations
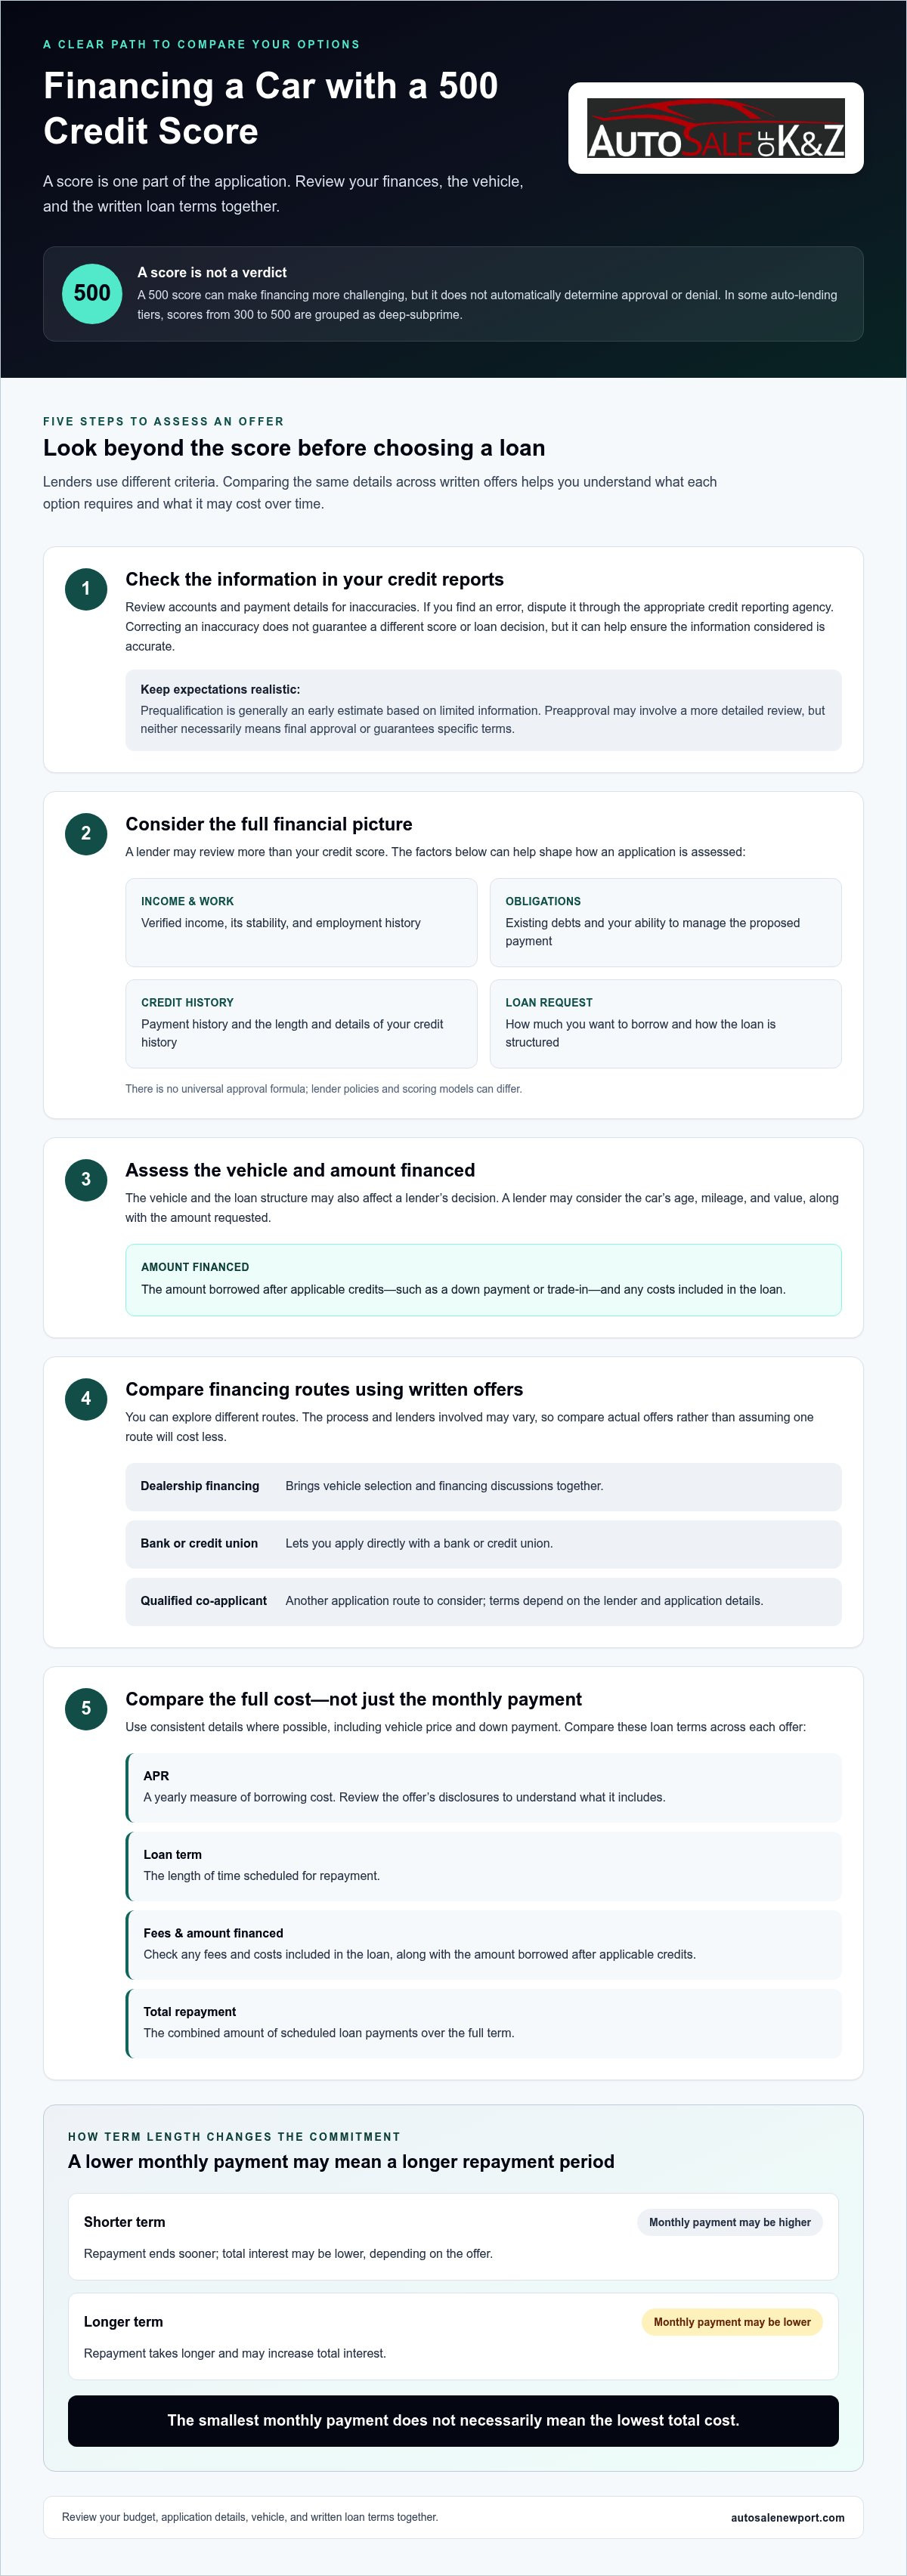
A 500 credit score can make financing more challenging, but it doesn’t automatically mean a lender will approve or deny your application. In some auto-lending tiers, scores from 300 to 500 are grouped as deep-subprime. Lenders use different scoring models and qualification criteria, so the score they review and how they assess your application may vary.
A credit score is one part of a loan application, not a verdict on the whole application. To understand how to finance a car with a 500 credit score, look at your finances, the vehicle, and the proposed loan terms together. A general overview of how auto financing works is available in Car finance on Wikipedia.
What does a 500 credit score tell a potential lender?
A low score may signal past credit difficulties, but it doesn’t explain your current ability to manage a payment on its own. Lenders may also consider payment history, verified income, existing debts, and the length and details of your credit history. Each lender weighs these factors according to its own criteria.
Before applying, review your credit reports for accounts or payment details that look inaccurate. If you find an error, dispute it through the appropriate credit reporting agency. Correcting an inaccuracy won’t guarantee a different score or loan decision, but it can help ensure the information being considered is accurate.
Does prequalification mean you are approved for a car loan?
No. Prequalification generally gives you an early estimate based on limited information. Preapproval may involve a more detailed review, but it isn’t necessarily a final commitment. These terms can vary by lender, so treat either as an indication to explore, not a promise of approval or specific loan terms.
A final decision may depend on verifying your application details and reviewing the vehicle and loan structure. The amount financed, vehicle details, income, and debts can all affect the lender’s decision. Before choosing a car, compare the written terms you receive rather than relying on an early estimate. That way, you can judge what the offer requires and whether it fits your budget.
How Lenders Evaluate a Car Loan Application Beyond Your Credit Score
Your credit score is one part of the review. A lender may also assess whether your income is stable and sufficient for the proposed payment, what you already owe, your payment history, and how much you want to borrow. There isn’t one universal approval formula: lender policies differ, and the same application may be assessed differently by different lenders.
The car itself matters, too. A lender may consider the vehicle’s age, mileage, and value when deciding whether it meets its financing criteria. The amount requested and the way the loan is structured can also affect the decision. Learning how to finance a car with a 500 credit score means reviewing both your application and the specific offer, rather than focusing on the score alone.
What do the key loan terms mean?
Use these terms to read and compare an offer:
- APR: The annual percentage rate, a yearly measure of borrowing cost. Review the offer’s disclosures to understand what it includes.
- Loan term: The length of time scheduled for repayment.
- Amount financed: The amount borrowed for the purchase after applicable credits, such as a down payment or trade-in, and any costs included in the loan.
- Total repayment: The combined amount of scheduled loan payments over the full term.
The FTC Consumer Advice on Car Financing offers further guidance on understanding and comparing financing terms.
How do APR and loan term affect the commitment?
A longer term spreads repayment over more time and may reduce the monthly payment, assuming other loan details stay the same. But it can also mean paying interest for longer, increasing the total repaid. When comparing offers, keep the vehicle price and down payment consistent where possible, then consider both the monthly payment and total repayment.
The smallest monthly payment doesn’t necessarily mean the lowest total cost. This illustrative comparison shows why it helps to consider both:
| Illustrative option | Monthly payment | Overall consideration |
|---|---|---|
| Shorter term | May be higher | Repayment ends sooner; total interest may be lower, depending on the offer. |
| Longer term | May be lower | Repayment takes longer and may increase total interest. |
To compare financing terms with used-car choices, explore Auto Sale Newport’s used-car inventory and consider how a potential vehicle fits your budget.
Which Car-Financing Options Can You Compare with a 500 Score?
There isn’t one financing route that fits every buyer. You can explore financing arranged through a dealership, apply directly with a bank or credit union, or consider applying with a qualified co-applicant. Loan terms depend on the lender and application details, so compare written offers rather than assuming one route will cost less.
Dealer financing versus applying through a bank or credit union
Dealer-arranged financing brings vehicle selection and financing discussions together, while a direct application lets you approach a bank or credit union yourself. The process and lenders involved can differ. For each written offer, compare the same details:
- APR: The annual borrowing-cost measure shown in the offer.
- Term: How long you have to repay.
- Amount financed: The amount borrowed for the purchase.
- Fees: Any listed charges connected with the financing.
- Total repayment: The scheduled amount paid over the full loan term.
Comparing the same details makes it easier to see how offers differ, even when their monthly payments look similar. For more local shopping context, read this guide to best used car deals in Fullerton.
When might a co-applicant or trade-in be relevant?
A co-applicant may be considered as part of a joint application, subject to the lender’s requirements and review of both applicants’ information. Applying together doesn’t guarantee approval or particular terms. A co-applicant also shares responsibility for the loan, so both people should understand the payment obligation and review the agreement before signing.
A trade-in valuation can help you plan by showing what your current vehicle may contribute toward the transaction. Its value may affect the amount you need to finance, but it doesn’t guarantee lender approval. Consider the vehicle and financing together: browse used cars for sale in Fullerton while keeping your budget and potential trade-in in view.
If you’re learning how to finance a car with a 500 credit score, make the next step a consistent comparison. Set the vehicle and purchase details beside each offer, then review the APR, term, amount financed, fees, and total repayment before deciding.
How to Prepare Before Applying for a Car Loan with a 500 Score
Preparing before you apply can make it easier to complete an application accurately and decide whether an offer fits your finances. If you’re researching how to finance a car with a 500 credit score, work through this checklist first:
- Review your credit reports. Look for errors, such as accounts or payment records you don’t recognize. Dispute inaccuracies through the appropriate credit reporting agency, and allow time for the issue to be reviewed.
- Set a realistic payment budget. Review your take-home income, recurring expenses, and existing debt obligations. Include regular vehicle costs in your planning, and decide what payment fits without relying on a lender’s maximum offer.
- Gather application documents. Prepare identification, proof of income, residence details, and information about the vehicle you’re considering. Requirements vary, so follow the lender’s instructions.
- Compare offers deliberately. Review written terms side by side, including APR, loan term, amount financed, fees, and total repayment. Don’t make a rushed decision based only on a quoted monthly payment.
What should you gather before submitting an application?
Commonly requested items may include a government-issued ID, recent income documentation, your current residence details, and vehicle information. A lender may request additional documents or use a different process, so treat this as a starting checklist rather than a complete application package.
Be ready to describe your income and regular obligations accurately. Include recurring household costs and debt payments in your budget review, even if a lender doesn’t request every detail. A clear picture can help you decide whether a proposed payment is manageable.
How can you compare offers without focusing only on payment?
Ask for the complete offer in writing, then compare the APR, term, amount financed, listed fees, and total repayment. A lower monthly payment can come with a longer repayment period, so give yourself time to review the full terms. If you’re considering multiple applications, follow a deliberate comparison plan. Credit-inquiry treatment depends on the scoring model and lender process, so check current guidance before applying rather than assuming every inquiry is treated the same way.
Once you’ve prepared your documents and know what terms to compare, explore used-car financing options at Auto Sale Newport as part of your Fullerton car-buying plan.
Find a Used Car and Financing Path in Fullerton That Fits Your Plan
Once you’ve considered your budget and how to compare loan terms, look at the vehicle and financing together. Auto Sale Newport is an independent used-car dealership in Fullerton, California, offering financing options for used-car purchases. Exploring the vehicle and potential financing in one place can help you assess how the purchase fits your plan, while remembering that an initial discussion isn’t a promise of approval.
What can local buyers expect when exploring financing at a dealership?
Shoppers can review used-car options, discuss dealership financing, and consider whether a trade-in belongs in their purchase budget. Auto Sale Newport offers trade-in valuations and on-site appraisals. A valuation can help you plan around your current vehicle, but it doesn’t guarantee financing or determine a lender’s decision. Lenders make decisions based on their own criteria and the details of each application.
Auto Sale Newport is located in Fullerton, a place to consider when comparing used-car options around Orange County. Shoppers researching from Anaheim, Buena Park, Santa Ana, Orange, Los Angeles, Riverside, Long Beach, Bakersfield, San Bernardino, Corona, or San Diego can keep the same priorities in view: a manageable payment, complete loan terms, and a vehicle that suits their needs. If you’re exploring how to finance a car with a 500 credit score, consider all three before deciding.
What should you do before choosing a car and signing?
Before making a decision, compare the written financing terms with your purchase plan and monthly budget. Review the APR, loan term, amount financed, fees, and total repayment. Then read the vehicle and loan documents carefully, making sure the details match what you’ve discussed. Take time to understand the payment schedule and full commitment before signing.
Auto Sale Newport is located at 1565 W Commonwealth Ave in Fullerton. You can explore Auto Sale Newport’s used-car inventory and financing options as you plan your purchase.
Approval, rates, and other terms depend on the lender and the application. Comparing the written details and choosing a payment that fits your budget can help you move forward with greater clarity.
Take Your Next Car-Buying Step with a Clear Plan
A 500 credit score can affect the financing terms available, but it doesn’t tell the whole story or determine a lender’s final decision. Understanding how to finance a car with a 500 credit score means looking beyond the score, preparing your financial information, and comparing written offers by APR, loan term, fees, and total repayment, not just the monthly payment.
Before choosing a vehicle, set a payment budget that works for your finances. If you’re shopping in Fullerton, Auto Sale Newport offers financing options for used-car purchases, along with trade-in valuations and on-site appraisals to help you plan. These can inform your purchase planning, but they don’t guarantee loan approval or specific terms.
Ready to take the next step? Explore used-car financing options at Auto Sale Newport and review the available information at your own pace. Careful preparation can help you make a more informed decision.
Frequently Asked Questions
Can I get approved for a car loan with a 500 credit score?
Possibly, but a 500 score doesn’t guarantee approval or automatically rule it out. Lenders may assess your income, existing debts, credit history, the vehicle, and the requested loan amount using their own criteria. An early prequalification or estimate isn’t necessarily a final decision. Before choosing a car, compare complete written offers and make sure the payment and total repayment fit your budget.
What do lenders consider besides my credit score when financing a car?
Lenders may review verified income, employment or income stability, existing debt obligations, payment history, and the amount you want to borrow. They may also consider the vehicle’s age, mileage, and value. There’s no single approval formula across lenders, so no one factor determines the outcome by itself. For a Fullerton purchase, prepare accurate financial information and compare the vehicle and loan terms together.
Will applying for a car loan with a 500 credit score lower my credit?
A lender’s formal application may result in a hard credit inquiry, which can affect your credit score. The effect varies by credit profile and scoring model. Some scoring models may group certain auto-loan inquiries made during a rate-shopping period, but the rules and time period can differ. Follow a deliberate comparison plan, and check how the lender handles credit inquiries before submitting applications.
How much of a down payment do I need with a 500 credit score?
There isn’t one required down payment for every borrower with a 500 score. Lenders set requirements based on the application, vehicle, and loan structure. Some lenders may expect a substantial down payment; industry guidance commonly cites 10% or more for borrowers with poor credit, but that isn’t a universal rule or approval guarantee. Ask how the down payment changes the amount financed and review the complete written terms.
Can a co-signer help me finance a car with a 500 credit score?
A qualified co-signer may strengthen an application, depending on the lender’s requirements and assessment of both people’s financial information. A co-signer also accepts responsibility for the loan if payments aren’t made as agreed, so this is a serious shared commitment. Discuss the obligation openly and review the loan terms together before applying. A co-signer can’t guarantee approval, a particular rate, or specific loan terms.
Is dealer financing or a bank loan better for a low credit score?
Neither route is automatically better. Dealer-arranged financing brings the vehicle purchase and financing process together, while a direct bank or credit-union application gives you another offer to compare. Availability and terms depend on the lender and your application. If you’re shopping in Fullerton, compare written offers using the APR, term, amount financed, fees, and total repayment, rather than choosing based only on the monthly payment.
What happens if I cannot afford the car loan terms I am offered?
You don’t have to accept terms that don’t fit your budget. Pause before signing, then consider whether a less expensive vehicle, a different loan structure, or more time to prepare could make the purchase manageable. Recheck your regular expenses and debts before deciding. If you’re exploring used-car financing in Fullerton, compare the written terms with your budget and proceed only if you understand and can manage the commitment.


