
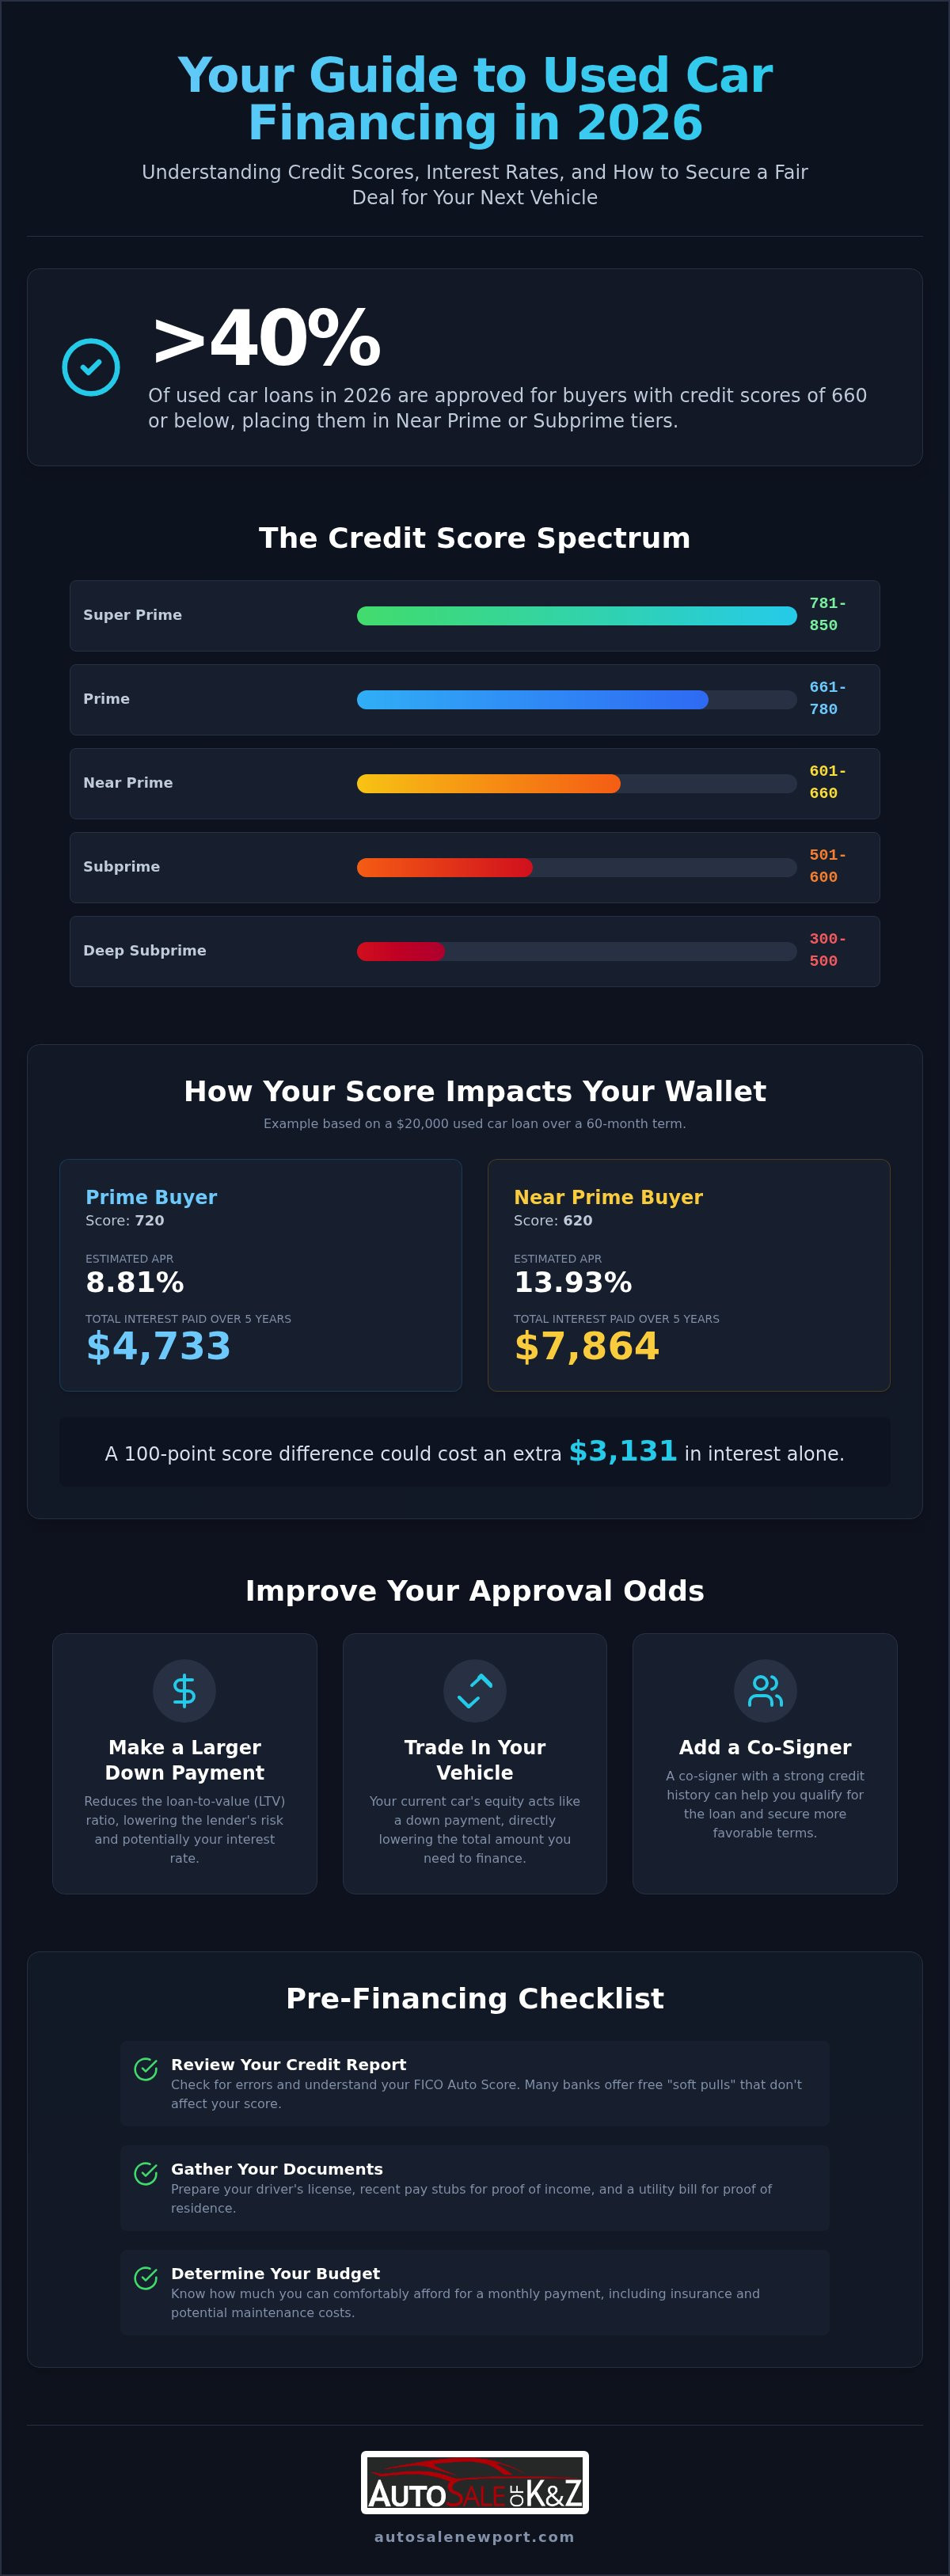
Did you know that more than 40% of used car loans in 2026 are approved for buyers with credit scores of 660 or below? If you've been losing sleep over a potential rejection, you aren't alone. Many drivers in Orange County feel the same anxiety, asking themselves exactly what credit score is needed to buy a used car without being overcharged. You shouldn't have to choose between a reliable commute and your financial future just because your score isn't currently in the "super prime" range.
We're here to provide a clear, supportive path forward for your next vehicle purchase in Fullerton. This guide breaks down the latest 2026 interest rate benchmarks and explains how the new California CARS Act protects your wallet from hidden costs. You'll learn how to leverage trade-ins to lower your loan-to-value ratio and discover why a premium used Tesla or a fuel-efficient Toyota Corolla is more attainable than you might think. By the end of this article, you'll have the tools to secure a fair deal and a reliable ride for your Southern California lifestyle.
Key Takeaways
- Learn exactly what credit score is needed to buy a used car in 2026 and how current lending tiers influence your loan approval.
- Understand the direct relationship between your credit score and your monthly payment to help you budget for a reliable vehicle in Southern California.
- Discover how trade-ins and co-signers can help you overcome lower credit scores to secure better financing terms on premium used models like Teslas and Toyotas.
- Get a step-by-step checklist of the documentation and credit report reviews required to ensure a smooth, transparent financing experience.
- See how a collaborative, low-pressure approach in Fullerton helps you navigate complex lender requirements to find the right fit for your financial situation.
Understanding Credit Score Ranges for Used Car Loans
When you start shopping for a vehicle in Fullerton, the first question on your mind is likely what credit score is needed to buy a used car today. In 2026, the landscape has shifted slightly as lenders adjust to stabilized vehicle prices. While the average used car buyer currently holds a score of 690, you don't necessarily need to be in the "Prime" category to drive home in a reliable Toyota RAV4 or a Honda Civic Sedan. Lenders generally categorize applicants into five tiers: Super Prime (781-850), Prime (661-780), Near Prime (601-660), Subprime (501-600), and Deep Subprime (300-500).
Used car loans often require more scrutiny than new car financing because the collateral, the car itself, is older. This is why more than 40% of used car loans are granted to individuals with scores of 660 or below. Lenders also distinguish between a "thin file," where a buyer simply hasn't built much history, and "bad credit," which reflects past payment struggles. A thin file is often easier to work with if you have a stable job and a local Orange County address. It shows you're a fresh start rather than a high risk.
The FICO vs. VantageScore Distinction
Understanding Credit Scores involves knowing which model a lender uses. Most Fullerton auto lenders prioritize the FICO Auto Score 8 or 9. These specific versions weigh your past car payment history more heavily than a standard credit card bill. If you've paid off a vehicle before, your auto-specific score might be higher than your general score. You can usually check these scores for free through your bank's mobile app, which uses a "soft pull" that won't hurt your credit standing before you visit the lot.
What Is the Minimum Score to Get Approved?
Is there a hard floor? Not exactly. While a score of 600 is often the gatekeeper for more competitive interest rates, we frequently see approvals for scores well below that mark. If your score is on the lower side, you can often bypass strict requirements by offering a larger down payment or using our on-site appraisal services to trade in your current vehicle. Lowering the loan-to-value ratio makes you a safer bet for lenders, even if you're looking at a premium used Tesla Model 3 or a Lexus IS Turbo. Our goal is to find a logical path forward that respects your budget and gets you behind the wheel without the high-pressure tactics found elsewhere.
How Your Credit Score Impacts Monthly Payments and APR
Your credit score acts as a financial thermostat, directly controlling the interest rate you'll pay on a vehicle loan. While we've discussed the tiers of credit, the actual dollar impact is where the math becomes real for your monthly budget. Lenders use your score to set the Annual Percentage Rate, or APR, which determines how much extra you'll pay for the privilege of borrowing. APR is the total yearly cost of borrowing, including fees. When you're researching what credit score is needed to buy a used car, it's helpful to look at the Average Credit Scores for Auto Loans to see where you stand compared to other Orange County drivers.
For a typical 60-month loan, even a small difference in your score can change your monthly payment by fifty or sixty dollars. Over the life of a five-year loan, those small monthly differences add up to thousands of dollars in "lost" money that could have gone toward your savings or local weekend trips. If you're looking at high-demand models like a used Tesla Model 3, the financing incentives might differ. Some lenders offer specialized terms for premium EVs, though they often require a more robust credit history to unlock the lowest possible rates.
The 'Credit Tax': Total Interest Over the Life of the Loan
Think of the difference between a 620 score and a 720 score as a "credit tax." A buyer with a 720 score might secure a Prime rate around 8.81%, while a buyer with a 620 score could face a Near Prime rate closer to 13.93%. On a $20,000 loan, the lower score could cost you an additional $3,000 in interest over five years. In high-cost areas like Fullerton or Riverside, where everyday expenses are already significant, interest compounding can quickly tighten your monthly budget. Choosing a shorter loan term can reduce the total interest paid, though it will increase your immediate monthly obligation.
Special Considerations for Financing Used EVs and Hybrids
California drivers often look for "green" vehicle incentives, but lenders view used EVs through a specific lens of risk. They prioritize battery health and the remaining warranty when assessing a loan application. A used Toyota RAV4 often qualifies for more straightforward financing because its high resale value provides a safety net for the bank. If you're curious about how your current vehicle might offset these interest costs, you can get a trade-in valuation online to see how a higher down payment could lower your APR regardless of your score.
Buying a Used Car with a Low Credit Score in Fullerton
If your credit history has hit a few bumps, you might feel like the traditional car-buying process is closed to you. It isn't. When asking what credit score is needed to buy a used car, many people overlook how much local relationships matter. National banks often use rigid algorithms that ignore your personal circumstances, but local Fullerton dealerships have deep ties with regional lenders who look at more than just a three-digit number. These lenders often consider your employment stability and your roots in the community when reviewing your application.
Adding a co-signer with a stronger credit profile is one of the most effective ways to lower your interest rate. This person shares responsibility for the loan, which gives the lender more confidence. It's a common strategy for younger drivers in Orange County who are just starting out or those rebuilding after a financial setback. Even without a co-signer, you can significantly improve your odds by focusing on your Loan-to-Value (LTV) ratio, which measures the loan amount against the car's actual worth.
The Power of the Down Payment
Lenders love to see "skin in the game." By providing a substantial down payment, usually between 10% and 20%, you lower the LTV ratio and reduce the lender's risk. How Lenders View Your Credit Score often changes when they see you've committed your own capital upfront. If you don't have cash on hand, you can use an on-site appraisal to turn your current vehicle into immediate equity. This reduces the amount you need to finance and makes you a much more attractive candidate for approval, even if you're eyeing a premium model like a Honda Civic Sedan or a Toyota Prius.
Avoiding 'Predatory' Lending Practices
Not all low-credit options are created equal. You should be wary of "Buy Here Pay Here" lots that don't report your on-time payments to credit bureaus. Without that reporting, you aren't actually rebuilding your score. Transparency is the most important factor when choosing a dealer. Under the new California CARS Act, dealers must disclose the total price clearly in all communications. Watch for these red flags in any contract:
- Hidden "add-on" fees for GPS trackers or protection packages.
- Lack of clarity regarding the final price after interest.
- Vague terms about whether your payments are being reported to build your credit.
A steady, reliable partner will prioritize your long-term financial health over a quick sale, ensuring you understand every line of the agreement before you sign.
Steps to Take Before Applying for Auto Financing
Preparation is the bridge between a rejected application and a set of keys in your hand. While you're researching what credit score is needed to buy a used car, remember that lenders also look at the accuracy of your financial story. Errors on credit reports are more common than many people think, and a single mistake regarding a late payment or an incorrect balance can unfairly depress your score. You should download your report from all three bureaus and dispute any inaccuracies at least two months before you plan to buy.
Setting a realistic budget is the next logical step. We often recommend the "20/4/10" rule of thumb to keep your finances stable. This means aiming for a 20% down payment, limiting the loan term to 4 years, and ensuring your total monthly auto expenses, including insurance, don't exceed 10% of your gross income. Following this structure helps you avoid becoming "car poor" in high-cost areas like Orange County. It also signals to lenders that you're a disciplined borrower, which can sometimes overcome a slightly lower score.
Quick Ways to Polish Your Credit Profile
If you have 30 days before visiting the lot, focus on reducing your credit utilization. This is the ratio of your credit card balances to your limits. Bringing this below 30% can provide a quick boost to your numbers. Even a 20-point increase can move you into a better rate tier. You should also avoid opening any new credit lines or making large purchases on existing cards during this window. New inquiries can cause temporary dips that might affect your APR at the last minute.
The Fullerton Buyer's Documentation Checklist
Lenders in Fullerton and the surrounding area require specific paperwork to verify your ability to pay. Having these documents organized prevents delays and shows the finance manager that you're prepared. If you're looking for used cars near Cal State Fullerton and dealing with student loans, be ready to show how your income covers all your obligations. Standard requirements include:
- Your two most recent pay stubs showing year-to-date earnings.
- Utility bills or a lease agreement as proof of residency in Southern California.
- The last three months of bank statements if you're self-employed or a 1099 contractor.
- A valid California driver's license and proof of auto insurance.
Gathering these items early ensures a transparent and low-pressure experience when you find the right Toyota Camry or Honda Civic Sedan. If you're ready to get started, you can begin your financing application online to see which programs fit your current profile.
Financing Your Next Vehicle at Auto Sale Newport
At Auto Sale Newport, we understand that the question of what credit score is needed to buy a used car often comes with a bit of stress. Our goal is to replace that anxiety with clarity. We operate as a steady, reliable partner for our neighbors in Fullerton, utilizing a vast network of lenders to find a financing structure that makes sense for the 2026 market. Because we specialize in high-volume inventory like the Tesla Model 3 and Toyota Camry, we have established relationships with financial institutions that understand the long-term value of these specific models. This expertise allows us to advocate for you more effectively than a general-purpose bank might.
Lenders appreciate the stability of high-demand vehicles like the Toyota RAV4 or the Lexus IS Turbo. Because these models hold their value exceptionally well, banks are often more willing to offer flexible terms to buyers who might fall into the subprime or near-prime categories. While other institutions might only see a three-digit number, we look at the logic of the transaction. We use our high-volume status to negotiate on your behalf, ensuring that the financing matches the quality of the vehicle you're driving home.
A Transparent, Low-Pressure Experience
Our team acts as a group of consultants rather than high-pressure salespeople. We want to find a payment that fits your life in Orange County, not just a one-time deal. We take pride in our community reputation and value long-term relationships, which is why we prioritize transparency throughout the entire process. We'll walk you through every variable of your loan, from the APR to the term length, so you feel empowered to make an informed decision. This supportive style helps lower the guard of our customers and creates an atmosphere of mutual trust.
Trade-in valuations are the secret weapon for many of our customers. When you bring your current vehicle in for an on-site appraisal, you're not just selling a car; you're creating immediate equity that can lower your interest rate. This is especially helpful if you're concerned about what credit score is needed to buy a used car, as a lower loan-to-value ratio often opens doors to lenders that might otherwise be hesitant. We provide fair, logical valuations that reflect the current market, helping you maximize the value of your trade-in toward a premium used Tesla or a reliable Toyota Prius.
Start Your Journey Today
You can browse our current selection of the Tesla Model Y or the Toyota Corolla online right now to see which features best fit your needs. Our digital tools make it easy to start the evaluation process from the comfort of your home. When you're ready for a more personal touch, visit our Commonwealth Ave showroom for a test drive and a quick, professional appraisal of your current vehicle. We're here to simplify the complex variables of auto financing and provide a clear path forward for every driver in Southern California.
Taking that first step toward a reliable vehicle doesn't have to be overwhelming. Whether you're a first-time buyer or looking to upgrade to a more efficient hybrid, our team is ready to share insights and provide the guidance you need. Get pre-approved for your next used car in Fullerton today!
Drive Home Your Next Vehicle with Confidence
Understanding what credit score is needed to buy a used car is just the first step toward ownership in Orange County. While current 2026 data shows that a score of 661 or higher often unlocks the best rates, your path to a reliable commute doesn't end if your numbers are lower. By gathering your documentation early and leveraging the equity in your current vehicle, you can navigate the financing process with clarity and ease. The right car should fit your lifestyle and your monthly budget without unnecessary stress.
Our team at Auto Sale Newport is here to act as your steady guide. We specialize in high-volume inventory like the Tesla Model 3 and Toyota RAV4; our consultative experts focus on transparency rather than pressure. You can visit us at 1565 W Commonwealth Ave for on-site appraisals that help lower your loan-to-value ratio and improve your terms. Whether you're rebuilding your credit or looking for a premium EV, we're ready to help you find a logical financial solution. Secure Your Fullerton Auto Financing Now and take the next step toward a vehicle you'll love driving every day.
Frequently Asked Questions
What is the absolute minimum credit score needed for a used car loan?
There is no official absolute minimum score required to secure a loan. While a higher score simplifies the process, many lenders in Fullerton specialize in subprime financing for scores below 500. Your approval often depends more on your steady income and the size of your down payment than just the three digit number. Understanding what credit score is needed to buy a used car helps you set realistic expectations for your interest rate.
Can I get a used car loan with a 500 credit score in California?
Yes, you can certainly secure a loan with a 500 credit score in California. The state has a robust market for subprime lending, and local dealerships often have relationships with specialized finance companies. You should be prepared to provide proof of residency in Orange County and a stable job history. A larger down payment or a reliable co-signer can also help you secure an approval with more favorable terms.
How much does a 700 credit score save you on a used car loan compared to a 600 score?
A 700 credit score can save you thousands of dollars in interest over the life of a typical 60 month loan. Moving from a Near Prime score of 600 to a Prime score of 700 can lower your APR by several percentage points. This shift often results in a monthly payment that is $60 to $100 lower, which keeps more money in your pocket for other Southern California living expenses.
Does a used Tesla require a higher credit score than a used Toyota?
Lenders look at the vehicle's resale value alongside your credit profile. While a Tesla Model 3 and a Toyota RAV4 both hold their value well, premium electric vehicles sometimes involve more detailed "ability to pay" assessments. However, specialized financing for used Teslas is available for many credit tiers. The high demand for these models in the LA and Riverside areas often makes lenders more comfortable with the collateral.
Will checking my credit at multiple dealerships hurt my score?
No, "rate shopping" within a short window will not significantly damage your credit standing. Credit bureaus recognize that car buyers often compare offers. As long as all your auto loan inquiries happen within a 14 to 45 day period, they are typically treated as a single hard pull. This allows you to find the most competitive rate in Fullerton without worrying about a major dip in your score.
How long do I need to be at my job to qualify for used car financing?
Most lenders prefer to see at least six months at your current job and two years of total continuous employment. If you have recently moved to Anaheim or Santa Ana for a new position, you might need to provide extra documentation like an offer letter. For self-employed buyers or 1099 contractors, providing three months of bank statements is a standard way to verify your stable income and ability to pay.
Can I use my tax refund as a down payment for a car in Fullerton?
Yes, using your tax refund as a down payment is an excellent strategy for buyers with credit challenges. Increasing your upfront payment reduces the loan-to-value ratio, which makes lenders more likely to approve your application. This is a common path for those asking what credit score is needed to buy a used car, as a substantial down payment can often override the requirements of a lower FICO score.
Is it better to finance through a bank or a dealership for a used car?
Both options have unique benefits depending on your financial situation. A local bank or credit union might offer a fixed rate for established members, but a dealership in Fullerton often has access to a wide network of multiple lenders. This creates a competitive environment where lenders vie for your business, frequently resulting in more flexible terms for buyers with unique credit profiles or those who have a vehicle trade-in.


