
A low down payment doesn’t have to come entirely from cash. For low down payment cars in Anaheim, financing and the value of a trade-in can affect how much you need upfront. Your down payment and loan terms depend on the vehicle, your financial situation, and the details of your trade-in.
It’s understandable to focus on the down payment first, especially when you’re balancing other expenses. But it’s also useful to consider the full financing picture: monthly payments, loan terms, and optional add-ons can affect the total cost of borrowing. A trade-in may reduce the amount you need to finance, depending on its value and any remaining loan balance.
This article explains how financing can work across different credit situations, what affects a trade-in’s contribution, and which details to review before choosing a car. You’ll get a clearer way to plan your upfront budget and next steps, without assuming one financing option fits everyone.
Key Takeaways
- Understand how credit history and loan details can shape financing options and the amount due upfront.
- See how a trade-in’s value and any remaining loan balance may affect the amount you need to finance.
- Learn what makes a down payment feel manageable by considering the full loan, not just the initial amount.
- Get a clearer picture of the documents that may support an auto loan application and why lender requirements can vary.
- Explore how to assess used-car options and decide whether a vehicle fits your budget and financing needs.
Financing for different credit situations
Credit history can influence the financing terms a buyer receives. Fees, optional add-ons, and any changes to financing after purchase also deserve attention.
According to the Consumer Financial Protection Bureau, optional features and services increase the total cost of a loan. The U.S. Government Publishing Office describes “yoyo sales,” where a dealer calls buyers back after they drive away, claiming financing fell through on the original terms.
Credit-Based Financing Options
Vehicle financing can depend on credit history, income, existing debt, and the vehicle being financed. A buyer with established credit may receive different terms from someone with limited or challenged credit. Compare the amount financed, interest rate, repayment schedule, and total loan cost, not just the monthly payment. These details help show whether the offer fits your budget.
Defining a Low Down Payment
There’s no single dollar amount that defines a low down payment in Anaheim. It means an upfront contribution that fits your available cash while leaving a manageable amount to finance. The vehicle price, trade-in equity, loan terms, and lender decision all affect the required amount. A smaller down payment leaves more of the purchase price to repay.
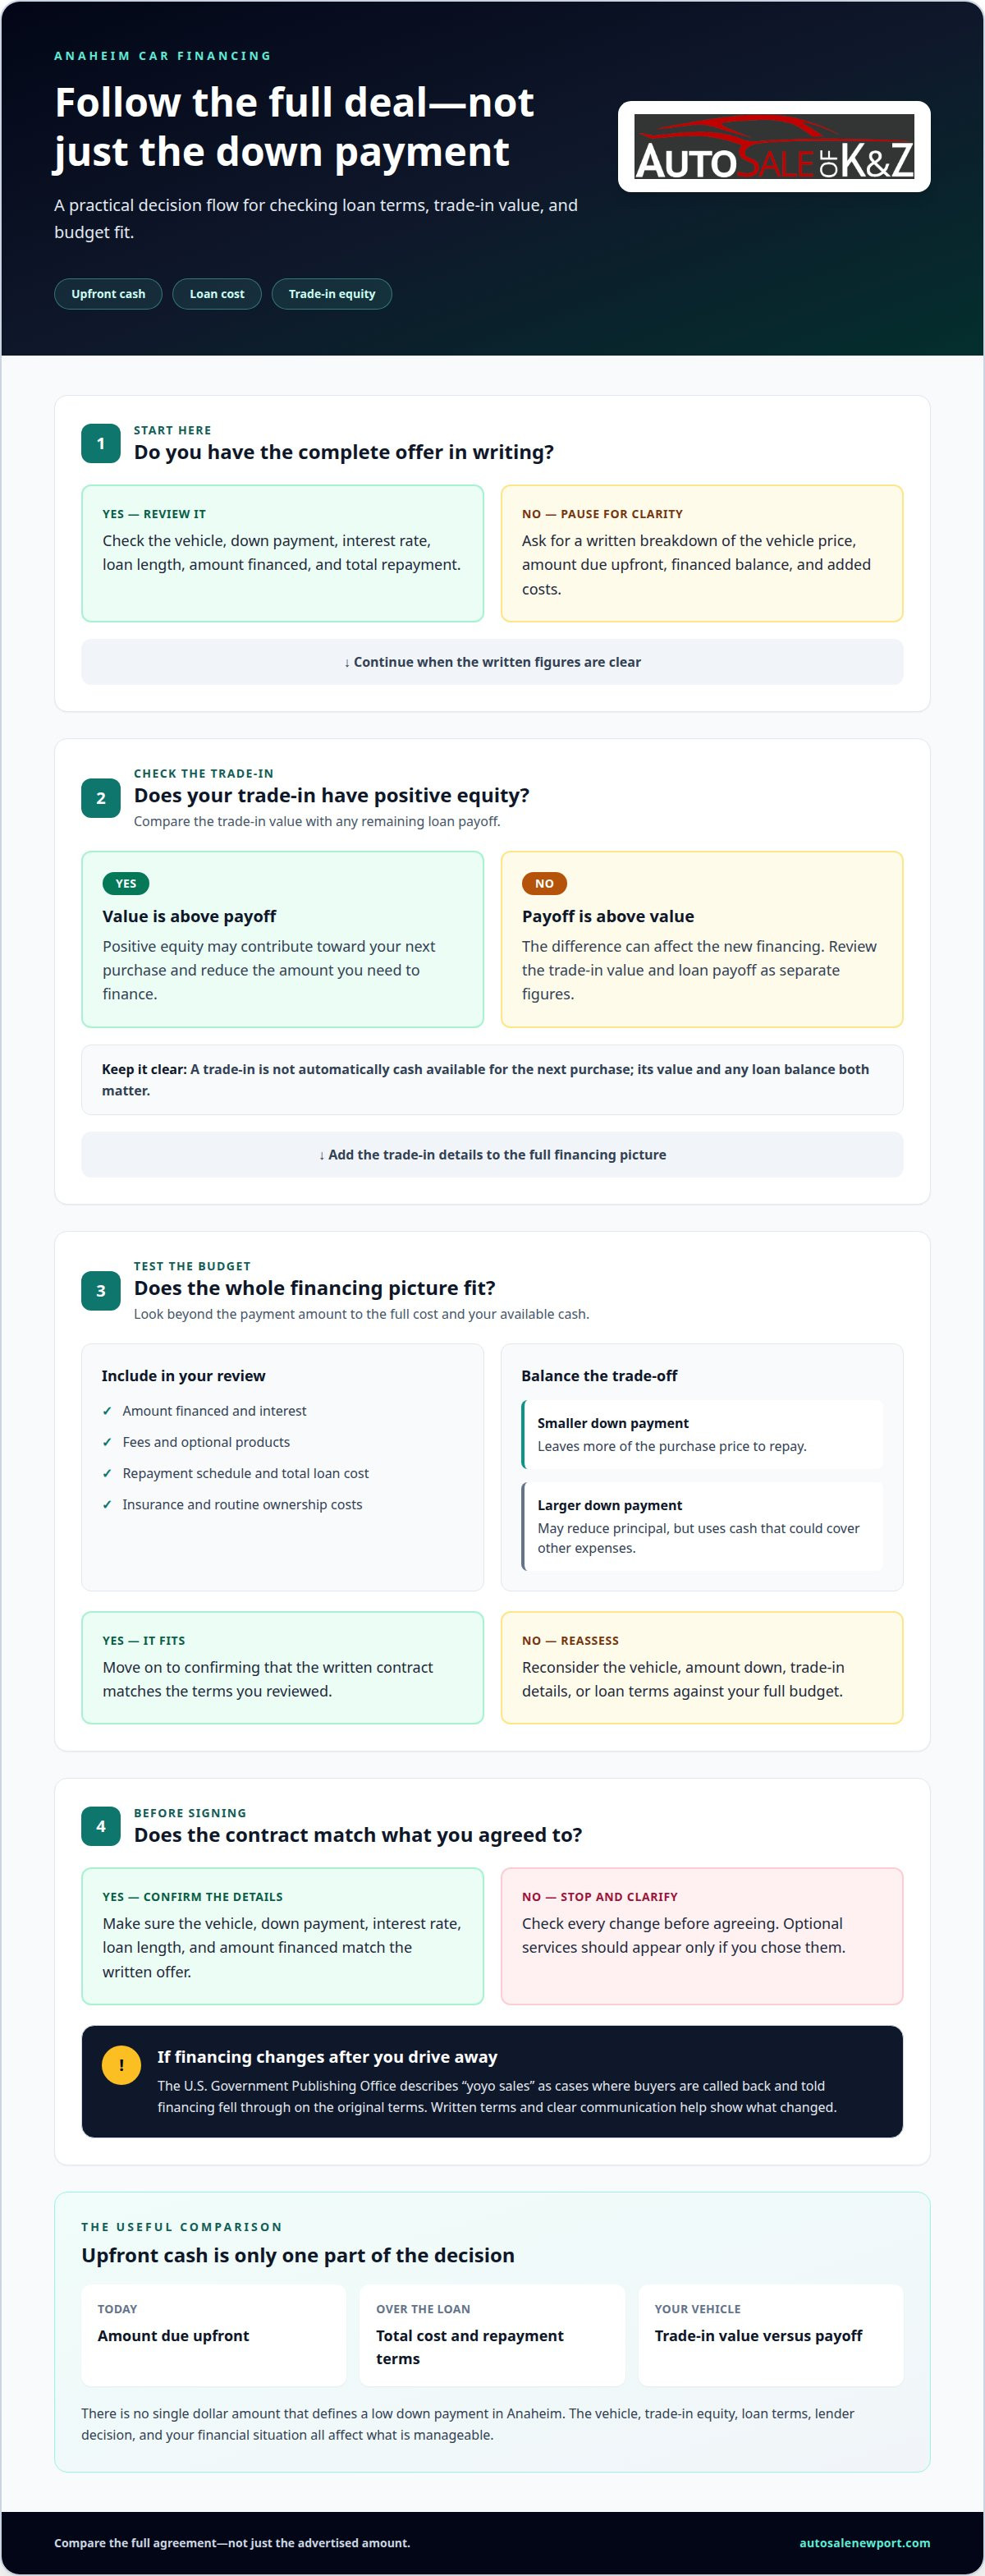
Start by separating the vehicle’s price from the loan’s full cost. Review the amount financed, interest, fees, and optional products together. An add-on may seem small by itself but still raise the total borrowing cost. Ask for the complete terms in writing before signing, including confirmation that extras are optional.
Credit challenges don’t make every financing path the same. Lenders assess each application based on its financial details, and terms can vary. A larger down payment may reduce the principal, but it also uses cash that could cover other expenses. Consider your full monthly budget, including insurance and routine ownership costs, before deciding how much to put down.
Trade-in equity can also affect the amount financed. A vehicle with positive equity may contribute toward your next purchase. If an existing loan balance exceeds the trade-in value, that difference can affect the new financing. Review the trade-in value and loan payoff as separate figures to understand how the deal is structured.
Before accepting an offer, match the contract to the terms discussed. Confirm the vehicle, down payment, interest rate, loan length, and total amount financed. Check that optional services appear only if you chose them. If financing terms change after you take the car, the U.S. Government Publishing Office’s description of yoyo sales shows why written terms and clear communication matter.
For low down payment cars in Anaheim, focus on the whole agreement, not just the amount due at signing. A sound comparison weighs upfront cash, the loan’s total cost, trade-in equity, and the repayment terms. This gives buyers with different credit situations a practical basis for deciding whether an offer fits.
Which Anaheim dealerships offer cars with low down payments?
Anaheim buyers can find low-down-payment options through dealerships that arrange vehicle financing. Available terms depend on the vehicle, application, and lender decision. An advertised down payment isn’t the whole deal. Compare the amount due upfront with the loan amount, interest, repayment schedule, and any added products. This is more useful than comparing headline payments alone.
Start with the specific vehicle you’re considering. Ask for a written breakdown showing its price, down payment, trade-in credit, and amount financed. Then review the proposed loan terms alongside that breakdown. Two dealerships might advertise similar upfront amounts but offer different loan lengths or financing terms. The full figures show how those differences affect what you’ll repay.
Use these steps to assess an Anaheim offer:
- Identify the vehicle. A down-payment offer applies to particular inventory or terms, so match it to the car you want.
- Request the complete figures. Separate the amount due at signing from the financed balance and added costs.
- Review the loan terms. Compare the interest rate, repayment schedule, and total repayment amount.
- Confirm the final agreement. Match the written contract to the terms presented before signing.
Ask whether the advertised amount depends on a trade-in, a particular vehicle, or approved financing. Each condition can change what you need upfront. If a trade-in is part of the deal, consider its value separately from any outstanding loan balance. This helps explain how the trade affects the new loan, rather than treating it as cash automatically available.
Also read the full contract before driving away. Optional services can increase the total loan cost, according to the Consumer Financial Protection Bureau. If financing terms change after delivery, pause before agreeing to new terms. The U.S. Government Publishing Office describes “yoyo sales” as situations where buyers are called back and told financing couldn’t be arranged as originally agreed. Written terms help clarify what changed.
A useful dealership comparison for Anaheim buyers focuses on the offer, not just the location or headline. Record each vehicle’s upfront amount, financing terms, trade-in treatment, and total repayment. Then consider whether the car and payment fit your budget. A low down payment can make a purchase feel more accessible, but the full financing agreement determines what you’ll owe over time.
What is considered a low down payment for a car in Anaheim?
In Anaheim, a low down payment means paying a smaller share of a vehicle’s purchase price upfront. There’s no single amount that feels low to every buyer. Your available cash, the vehicle price, trade-in equity, and financing terms all affect the answer. Judge the down payment alongside the amount financed, not on its own.
Use this simple example without assuming a particular dollar figure. Subtract the down payment from the car’s purchase price to find the starting balance before other costs. A smaller upfront amount leaves more of the purchase price to finance. That can make the initial payment easier to manage while increasing what you repay through the loan.
To assess an offer in Anaheim, separate these figures:
- Due at signing: the cash required to complete the purchase.
- Down payment: the portion applied toward the vehicle’s purchase price.
- Amount financed: the balance included in the auto loan.
- Total repayment: the amount paid over the loan term, including financing costs.
These figures answer different questions. The amount due at signing shows your immediate cash need. The amount financed shows how much debt the loan creates. Total repayment helps reveal the longer-term cost. Two Anaheim offers could require similar cash upfront but have different loan terms. Comparing only the initial payment would miss that difference.
A trade-in can also change the calculation. First, distinguish the vehicle’s trade-in value from any loan balance still attached to it. Positive equity may contribute toward your next purchase. If the payoff exceeds the trade-in value, the shortfall can affect the amount financed. Keeping those figures separate makes the down payment’s contribution easier to understand.
Think about your budget in steps. First, decide what cash you can use without relying on a loan. Next, account for any trade-in equity. Then review how the proposed down payment changes the amount financed and repayment terms. Finally, consider regular ownership costs alongside the car payment. This approach defines “low” by your budget, not an advertised label.
For low down payment cars in Anaheim, compare the complete written offer. Review the vehicle price, upfront amount, trade-in treatment, financing costs, and total repayment together. A smaller down payment can meet an immediate cash limit, but it doesn’t automatically mean the loan costs less. Choose an arrangement based on both the cash needed today and the obligations that follow.
What documents do Anaheim dealers require for low-down-payment auto loans?
Auto loan applications use documents to support details about identity, income, and residence. The exact paperwork depends on the lender and your situation. Prepare a clear set of documents before discussing a specific car. This makes it easier to provide consistent information across the application and financing documents.
Start with identification and contact details. A current government-issued photo ID can help establish your identity. Keep your name and address consistent across application materials. If the address on your ID is old, prepare a document showing your current residence. Depending on what the lender accepts, a recent utility bill or bank statement may be useful.
Income records help show the funds available for loan payments. If you receive wages, prepare recent pay statements. If you’re self-employed, organize records showing business income. If you have more than one income source, list each one clearly. Lenders use application details to assess financing, so accurate information matters more than a large pile of documents.
- Identity: keep a current photo ID available.
- Income: gather pay statements or relevant income records.
- Residence: prepare a document with the current address.
- Trade-in: bring vehicle and loan details if trading a car.
- Application: provide accurate employment and contact information.
A trade-in adds its own paperwork. Bring the vehicle’s registration and title information if available. If a loan remains, include the lender name and account details. These records help distinguish the car’s value from the amount still owed. A trade-in with an outstanding balance affects the financing calculation differently from a vehicle owned outright.
Before submitting an application, review each entry for accuracy. Check spelling, address, employer information, and income figures against your documents. Keep copies accessible, but share personal records only through the lender’s application process. Don’t sign blank forms or leave key loan terms unclear. A complete application can help prevent avoidable delays caused by missing or inconsistent details.
Bring documents that match your situation rather than assuming every buyer needs the same paperwork. An employee with one income source may prepare different records from a self-employed buyer with a trade-in. The lender’s application determines which details are needed for review. For low-down-payment financing, the down payment doesn’t replace identity or income information. The application still needs a clear account of your circumstances and proposed vehicle purchase.
Keep the final loan documents with your application records. Review the down payment, amount financed, and repayment terms in the written agreement before signing. If a figure differs from what you discussed during the application, resolve the discrepancy before completing the paperwork. Organized records make it easier to follow each step from application through signing.
Are low-down-payment car offers in Anaheim available for used and certified pre-owned cars
Used cars can be financed with a low down payment, depending on the vehicle and loan terms. A certified pre-owned label doesn’t determine the down payment. The car’s price, age and condition, your application, and lender terms all shape the financing decision. Review each vehicle and loan as a specific package.
For a used car, start with the amount due upfront and the amount financed. Then consider the repayment schedule and total loan cost. A lower initial payment can leave more of the purchase price to repay. Even similar used cars may have different loan terms, depending on their details and the financing offer.
Certified pre-owned describes a vehicle’s certification status, not a particular financing arrangement. That status alone doesn’t tell you how much cash you’ll need upfront. The vehicle price and financing terms still matter. A certified car and a non-certified used car could require different down payments because their prices or loan offers differ.
Compare both types using the same details:
- Vehicle: identify whether it’s used or certified pre-owned.
- Upfront amount: record what the written offer requires at signing.
- Loan: review the amount financed and repayment schedule.
- Total cost: include interest and any optional products.
- Vehicle records: review the specific certification information presented for that car.
Certification helps describe the vehicle, while financing terms explain the payment arrangement. Don’t assume certification means a lower down payment or a better loan. Instead, assess the car’s price, condition, certification details, and financing terms together. This makes comparisons more useful than relying on labels in an advertisement.
Trade-in equity can also contribute toward a purchase, whether you’re considering a used or certified pre-owned car. First, separate the trade-in value from any remaining loan balance. The equity left after accounting for that balance can affect the amount financed. A trade-in with an outstanding loan needs a different calculation from one owned outright.
Before signing, match the written agreement to the vehicle and financing terms discussed. Check the down payment, amount financed, interest, repayment schedule, and optional add-ons. The Consumer Financial Protection Bureau notes that optional features and services increase a loan’s total cost. A clear comparison helps you decide whether the upfront amount fits your budget without overlooking later payments.
For Anaheim shoppers, the practical answer is that used-car financing can involve a low upfront payment, while certified status doesn’t determine that amount. Compare the full terms for each individual vehicle. Explore used-car financing options as you consider which type fits your budget and priorities.
Auto Sale Newport
Auto Sale Newport can help you consider how a trade-in fits into a used-car purchase. If you’re weighing upfront cash against vehicle choices, it helps to look at both together. Options include pre-owned models such as the Tesla Model 3, Toyota Prius, and Toyota Corolla. Their prices and financing terms depend on the specific vehicle and purchase details.
A trade-in valuation can clarify how your current vehicle may contribute to your next purchase. Consider that value alongside the down payment and full loan terms, rather than treating it as guaranteed cash. This can give you a practical starting point for discussing a car that suits your needs.
If you’re ready to discuss your options, contact Auto Sale Newport.
Take the Next Step Toward a Car That Fits
Choosing among low down payment cars in Anaheim starts with matching the vehicle to your priorities, not just its upfront cost. Consider how you’ll use the car, what monthly commitment feels workable, and whether a trade-in belongs in your plan. If a Tesla Model Y is on your shortlist, compare it just as carefully as any other option.
Before moving forward, decide which details matter most to you. A clear idea of your preferred vehicle and budget can make the next conversation more focused. You can discuss available vehicles and how trade-in value may fit into a purchase, then consider the financing details in context.
When you’re ready to explore your next step, contact Auto Sale Newport. A thoughtful decision begins with the questions that matter to you, and you can take them one at a time.
Frequently Asked Questions
What are the minimum down payments and monthly payments for cars at Anaheim dealerships?
There isn’t one minimum down payment or monthly payment for every Anaheim purchase. The vehicle, credit history, income, loan amount, and lender approval all affect financing terms. Listed vehicle prices exclude taxes, license, registration, finance charges, and other government-required fees. Verify vehicle, pricing, and advertising details before purchasing. Auto Sale Newport isn’t responsible for typographical, pricing, product-information, or advertising errors.
At Auto Sale Newport, financing is subject to lender approval and may vary based on credit history, income, vehicle, loan amount, and other factors. Review the written breakdown of the amount due at signing, financed balance, and other charges. A zero down payment alone doesn’t explain the complete purchase terms.
What credit score or income is needed to qualify for low-down-payment car financing in Anaheim?
There isn’t one credit score or income figure that applies to every application. Lenders assess credit history, income, the vehicle, and loan amount when reviewing financing. Two applicants seeking the same car may receive different terms because their financial details differ. Auto Sale Newport facilitates financing, but approval and terms depend on the lender’s review of each application.
How do low-down-payment car loans affect interest rates and total cost?
A smaller down payment leaves more of the purchase price to finance, which can increase borrowing costs over the loan. The interest rate and repayment schedule also affect total repayment. According to the Consumer Financial Protection Bureau, optional features, services, or add-ons increase the total cost of a loan. Compare the amount financed and full repayment total, not only the initial cash due.
How can buyers compare low-down-payment financing with leasing or a larger down payment in Anaheim?
Compare the written terms with your priorities. A larger down payment reduces the amount borrowed, while a smaller one preserves more cash upfront. Financing and leasing have different payment structures and end-of-term arrangements, so review each agreement’s obligations. Consider how long you want to keep the vehicle and whether ownership matters. Compare total commitments rather than judging by the first payment alone.
Are there local credit unions or lenders near Anaheim offering low-down-payment auto loans?
Credit unions and other lenders are possible auto-financing channels for Anaheim buyers, but terms depend on the lender and application. Auto Sale Newport facilitates vehicle financing subject to lender approval. Compare a lender’s written rate, repayment schedule, amount financed, and required upfront payment. You may also arrange an independent third-party vehicle inspection at your own expense, subject to dealership and vehicle availability.


