
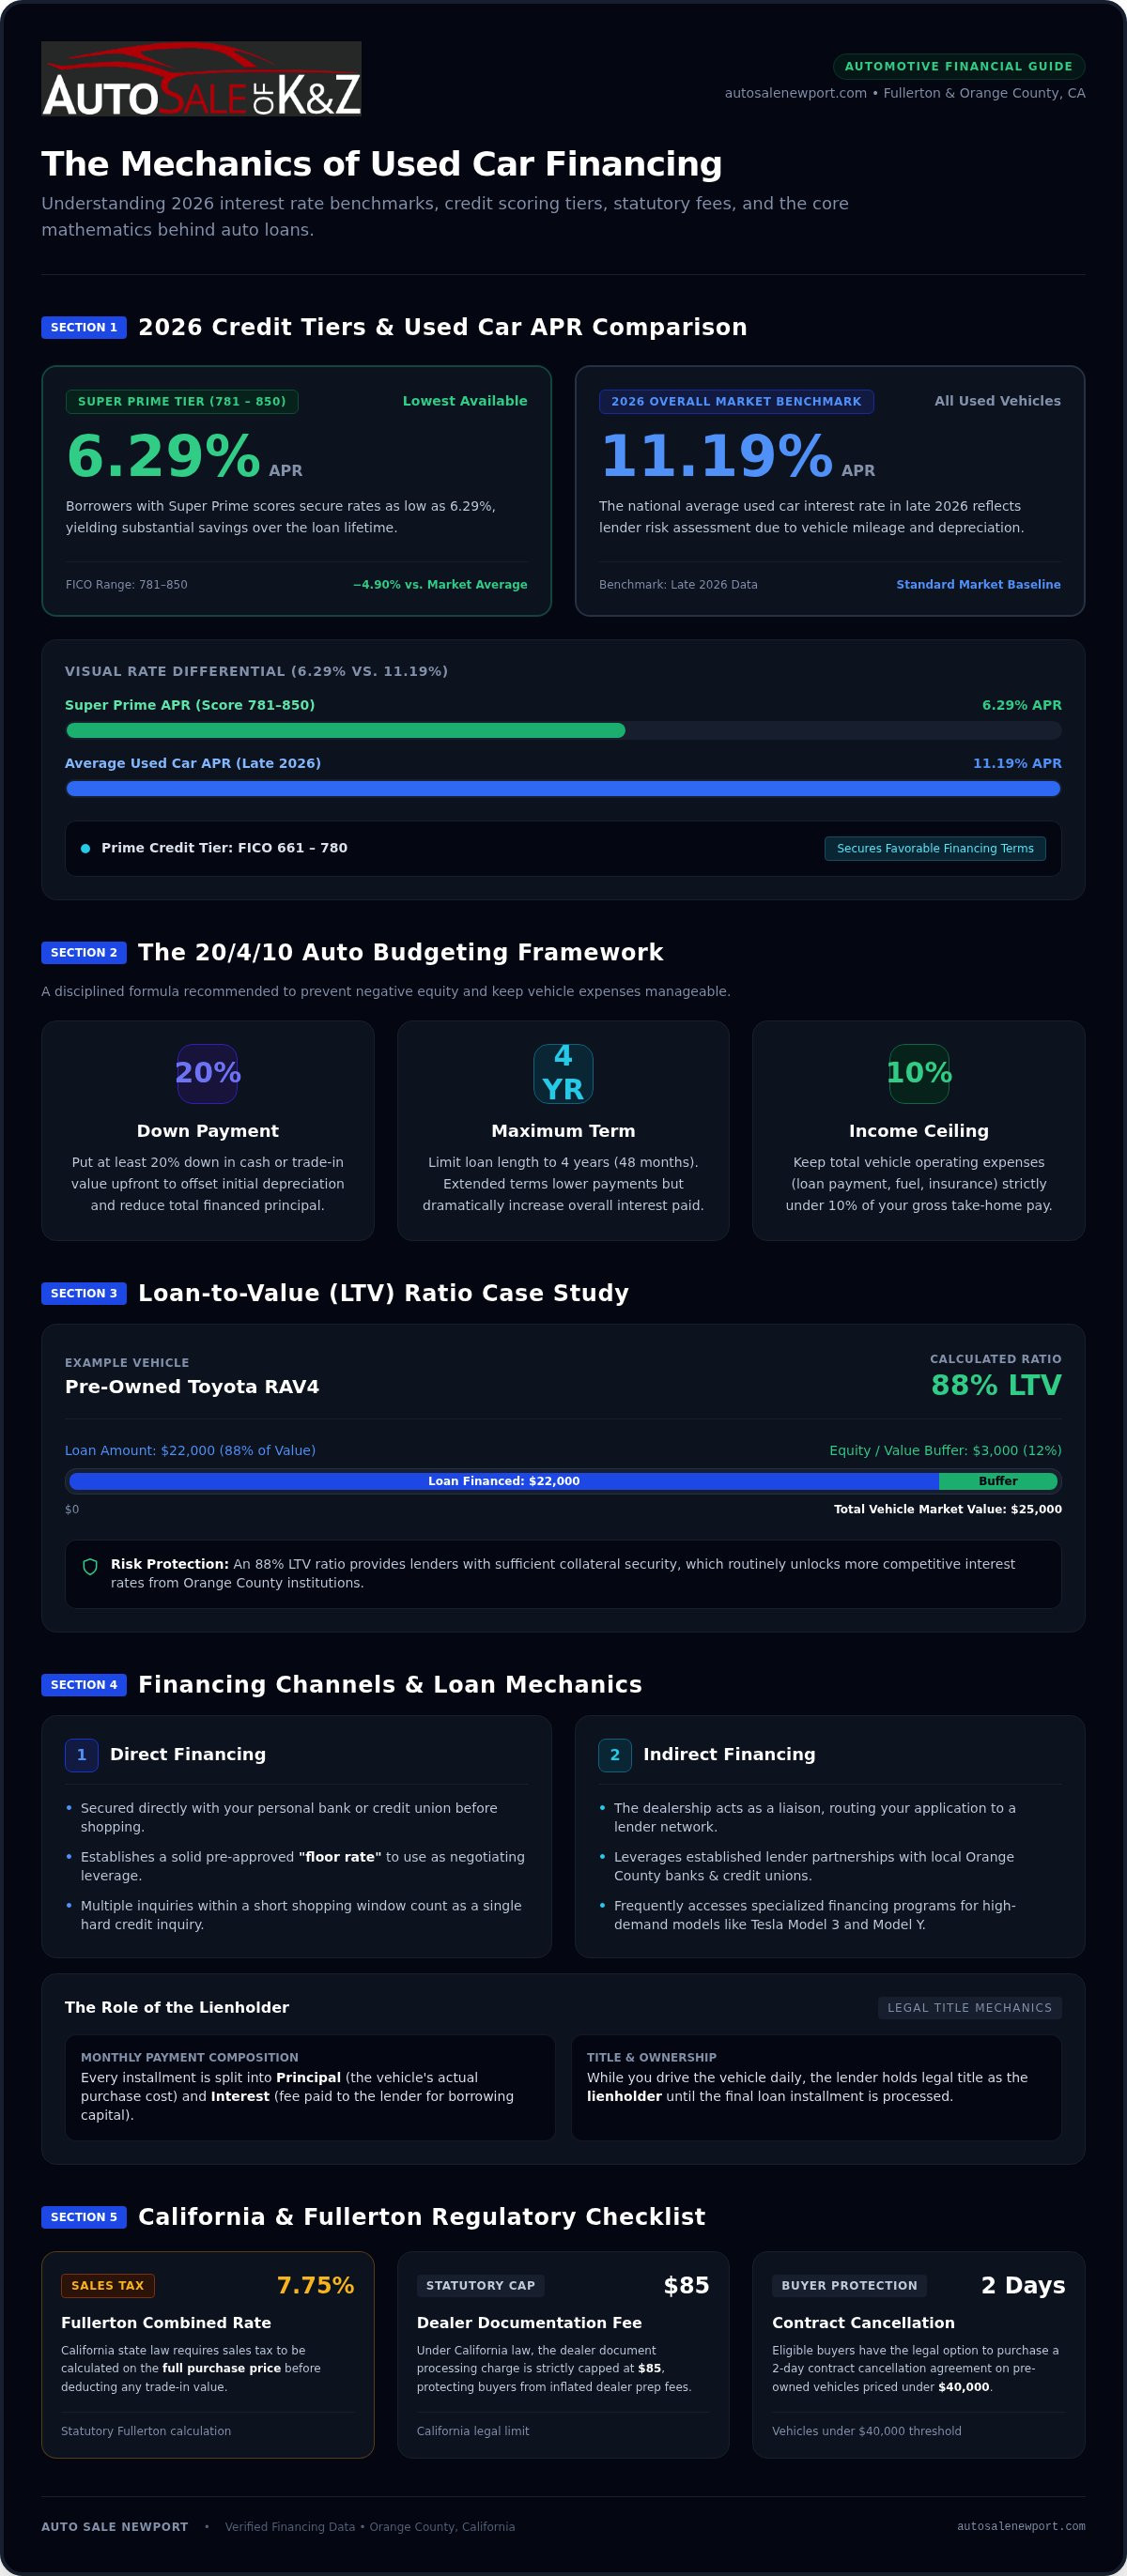
Did you know that while the average used car interest rate in 2026 is 11.19%, drivers with super prime credit scores are currently securing rates as low as 6.29%? It is a significant gap, and it's completely normal to feel some anxiety when you start looking at those numbers. Most buyers we talk to in Fullerton are worried about hidden fees or whether their monthly payment will actually be affordable in the long run. You want transparency, not a high-pressure sales pitch, and you deserve to know exactly where every dollar is going.
We're here to pull back the curtain and explain exactly how does used car financing work so you can shop for a Toyota RAV4 or a Tesla Model 3 with total confidence. Our goal is to help you master the mechanics of used car loans, from understanding how your credit score dictates your APR to calculating the 7.75% Fullerton sales tax. We will walk you through the entire process, including how to secure pre-approvals and how your trade-in value helps lower your loan principal. By the time you finish reading, you'll have a clear roadmap to a fair deal and a local partner you can trust.
Key Takeaways
- Learn exactly how does used car financing work by exploring the mechanics of loan terms and the role of the lienholder.
- Understand the 2026 credit score tiers and how to use the 20/4/10 budgeting rule to keep your monthly payments affordable in Orange County.
- Evaluate the pros and cons of different lenders, from traditional banks to local Fullerton credit unions, to secure the best rate for your needs.
- Discover how to maximize your trade-in equity and down payment to significantly lower your total interest and monthly costs.
- See how a transparent, local dealership can act as a guide for finding specialized financing on high-demand vehicles like the Tesla Model 3.
What is Used Car Financing and How Does It Differ from New?
So, how does used car financing work for the average buyer? At its core, used car financing is the process of borrowing capital from a lender to cover the purchase price of a pre-owned vehicle. Instead of paying the full amount upfront, you pay it back over time with interest. While you get to drive the car every day, the lender acts as the lienholder. This means they hold the legal title until your final payment is processed. Understanding the mechanics of car financing helps you see that your monthly payment is a mix of principal, which is the car's actual cost, and interest, which is the fee for the loan.
You might wonder why interest rates for used cars are typically higher than those for new ones. Lenders view pre-owned vehicles as higher risk because their market value is harder to predict and they have existing mileage. As of late 2026, the average used car APR sits around 11.19 percent. This reflects the lender's risk assessment regarding the vehicle's age. By focusing on a reliable model like a Toyota Corolla or Camry, you can often provide the lender with more confidence in the collateral, which helps keep your terms fair and manageable.
Direct vs. Indirect Financing: Know the Difference
If you're asking how does used car financing work at a dealership, the answer is usually indirect financing. In this scenario, the dealership acts as a liaison, sending your application to a network of local Orange County credit unions and banks to find the best fit. Direct financing, on the other hand, involves getting a pre-approval from your own bank before you ever step onto the lot. Both paths have merits. A pre-approval gives you a solid baseline, but a dealership's established relationships can often uncover specialized terms for specific inventory like a Tesla Model 3.
The Concept of Loan-to-Value (LTV) Ratio
Lenders use the Loan-to-Value (LTV) ratio to determine how much risk they're taking on. This ratio compares the loan amount to the actual market value of the car. If you choose a vehicle with high resale value, like a Tesla Model Y, you might find it easier to get approved. A high resale value means the car is worth more if the lender ever has to recover their investment. In 2026, a $22,000 loan for a used Toyota RAV4 valued at $25,000 results in an 88% LTV ratio, which often secures a more competitive interest rate from local Orange County lenders.
5 Steps to Securing a Used Car Loan in Fullerton
Securing a loan doesn't have to be a mystery. If you're wondering how does used car financing work in practice, it follows a logical five-step path designed to protect your wallet. The process begins long before you pick out a Toyota Camry or a Tesla Model Y. It starts with preparation. By the time you reach the dealership, you should have a clear understanding of your credit standing, a firm budget, and all your paperwork in order. This structured approach ensures you remain in control of the transaction from start to finish.
Step 1: Auditing Your Credit Health
Lenders in 2026 use FICO tiers to determine your risk. Super Prime buyers (781 to 850) often secure the most competitive rates, while Prime buyers (661 to 780) still find very favorable terms. It's vital to check your report for errors that could unfairly spike your APR. While shopping, remember that multiple credit inquiries for an auto loan within a short window usually count as a single "hard pull," so you don't need to fear comparing offers. Consulting the Federal Trade Commission's vehicle financing guide can help you understand the legal protections you have during this evaluation phase.
Step 2: Calculating Your 'Real' Budget
A common mistake is budgeting only for the monthly payment. In Fullerton, the combined sales tax rate is 7.75 percent. California law requires this tax to be calculated on the full purchase price before any trade-in value is deducted. We recommend the 20/4/10 rule: put 20% down, choose a 4-year term, and keep your total monthly car expenses under 10% of your take-home pay. Using a used car financing calculator allows you to simulate these costs and see how they fit into your Southern California lifestyle.
Once your budget is set, gather your proof of income, residency, and identity. Getting a pre-approval from a local credit union provides a "floor" rate, which gives you leverage when finalizing terms. When you're ready to sign the retail installment contract at the dealership, pay close attention to the details. In California, the dealer documentation fee is capped at $85. You should also be aware of the 2-day contract cancellation option for vehicles under $40,000. If you want to see how your current vehicle fits into this math, you can start with a transparent trade-in appraisal to see your real-world buying power.
Sources of Financing: Banks, Credit Unions, and Dealerships
Where you choose to borrow money is a major factor in your overall cost. If you're asking how does used car financing work across different institutions, it's helpful to view them as tools for different needs. Traditional banks are reliable if you have a long-standing relationship, but they often stick to very strict credit requirements that can be hard to meet. Online lenders have become a popular digital-first option in 2026, offering speed and convenience for shoppers who prefer to handle everything from their smartphone before visiting a lot in Fullerton. These digital platforms are great for quick quotes, but they lack the personal touch of a local partner.
The Advantage of Local Fullerton Dealership Financing
One of the biggest perks of working with a local partner is their network. While you might only have time to apply at one or two banks yourself, a dealership's finance office can submit your application to multiple regional lenders simultaneously. This "one-stop" approach isn't just about saving time; it's about finding the right fit. Because dealerships move a high volume of vehicles, they can sometimes "buy down" interest rates for qualified buyers. This means we can effectively secure a lower APR for you than you might get as an individual applicant, especially for high-demand models like the Toyota Prius or Camry.
Credit Unions: The Orange County Secret
In Orange County, credit unions are often the unsung heroes of auto loans. Institutions like SchoolsFirst FCU or Orange County’s Credit Union frequently offer APRs that are 1.5 percent to 2.5 percent below commercial bank averages. These member-focused lenders favor local accountability and long-term residency, which can be a huge benefit for Fullerton families. Understanding how does used car financing work at a credit union versus a bank can save you thousands over the life of your loan.
Membership requirements vary, but many are open to anyone who lives or works in the area. Before making a final decision, we suggest reviewing CFPB auto loan resources to help you compare these member-exclusive terms against other offers. Bringing a credit union pre-approval to the dealership is a smart move. It gives us a baseline to beat, and it helps us ensure you get the most transparent and neighborly deal possible for your next vehicle purchase.
How Your Trade-In and Down Payment Lower Your Costs
If you want to understand how does used car financing work at a deeper level, you have to look at the relationship between your upfront contribution and your long-term interest. Most people think of a down payment as just a way to lower the monthly bill. While that's true, it actually does something much more important: it reduces the loan-to-value (LTV) ratio. For buyers with a "thin" credit file or a score that's still growing, a strong down payment or a high-value trade-in can be the difference between a quick approval and a long negotiation.
In California, there's a specific detail you should know regarding taxes. Unlike some other states, California assesses the 7.75 percent sales tax on the full purchase price of the vehicle before your trade-in is deducted. Even though you don't get a direct tax credit on the trade-in itself, that equity acts as a cash equivalent that lowers the principal you need to borrow. By borrowing less, you pay less interest over the life of the loan. If you're trading in a reliable model like a Toyota RAV4, that equity can significantly offset the cost of your next vehicle.
Maximizing Your Vehicle Trade-In Value
Getting the most for your current car is a key part of the process. While online estimates give you a rough idea, an on-site appraisal at Auto Sale Newport provides a firm number based on the local Fullerton market. Before you bring in your Toyota or Honda, spend a little time on basic detailing and gather your maintenance records. A well-documented history can often lead to a higher valuation because it gives the next buyer more confidence. For more tips, check out our vehicle trade-in value guide to help you prepare.
The Math of the Down Payment
Knowing how does used car financing work from a mathematical perspective helps you plan for the future. Every $1,000 you put down typically reduces your monthly payment by about $15 to $20, depending on your interest rate. Finding the "sweet spot" is about balancing your available cash with the long-term savings on interest. In 2026, the recommended 20 percent rule for used car down payments remains the gold standard because it helps you avoid negative equity, where you owe more than the car is worth. This is especially helpful if you're looking at a high-demand model like a Tesla Model 3, as it ensures your loan stays in line with the car's actual market value.
We believe in making this math as clear as possible so you can shop with total confidence. If you're ready to see what your current car is worth, get a professional trade-in appraisal at our Fullerton showroom today.
Financing Your Next Vehicle at Auto Sale Newport
Selecting the right vehicle is an exciting milestone, but choosing a dealership that values your peace of mind is what makes the experience truly successful. We believe that understanding how does used car financing work should be a straightforward, empowering process rather than a source of stress. Our team at Auto Sale Newport is dedicated to maintaining a balanced blend of professional confidence and neighborly warmth, ensuring you feel like a partner in this decision. We don't use high-pressure tactics; instead, we focus on transparency to lower your guard and provide the clarity you deserve.
Whether you're looking for a fuel-efficient Toyota Corolla or exploring our used Tesla Model 3 inventory, we treat the financing process as a collaborative evaluation. We specialize in high-volume Toyota and Tesla models, which means we understand the specific resale values and lender requirements for these vehicles. Our on-site appraisals are designed to be quick and fair, providing you with instant trade-in credit that can be applied directly to your purchase. This local accountability is why so many buyers in the area trust us with their significant financial decisions.
A Low-Pressure Approach to Auto Loans
Our team operates on a consultant model, which means our primary goal is to help you find the loan that fits your life. If you've spent hours researching how does used car financing work, you'll find that our experts are ready to translate those complex variables into a clear, monthly plan that fits your budget. We take pride in serving our neighbors across Fullerton, Anaheim, Santa Ana, and the broader Orange County community. If you're ready to see how easy the process can be, we invite you to schedule a test drive and a no-obligation finance consultation to explore your options.
Ready to Drive? Visit Us in Fullerton
Finding us is easy. Our showroom is located at 1565 W Commonwealth Ave, Fullerton, CA 92833. We encourage you to browse our latest inventory of the best used cars for sale in Fullerton before your visit. To make your first financing discussion as efficient as possible, please bring the following items:
- A valid driver's license to confirm your identity and residency.
- Proof of income, such as your most recent pay stubs or bank statements.
- Current vehicle documentation if you plan to utilize our on-site appraisal service for a trade-in.
- Proof of insurance to ensure you're ready to drive home safely.
We look forward to acting as your steady, reliable guide through every stage of the car-buying journey. Visit us today to experience a different, more supportive approach to auto financing.
Your Path to Confident Car Ownership in Fullerton
You now have a clear roadmap for your car-buying journey in Orange County. We have explored the mechanics of loan-to-value ratios and the specific steps to secure a fair rate. By understanding how does used car financing work, you can approach any lender with the confidence of a seasoned expert. Whether you are maximizing your trade-in value or comparing local credit union offers, you are now in total control of the transaction and your financial future.
At Auto Sale Newport, we take pride in being more than just a dealership; we are your neighborly guide through this significant financial decision. As independent specialists in Tesla and Toyota models, we offer on-site appraisals in Fullerton to ensure you get the instant credit you deserve. We have served the Orange County community for years by prioritizing transparency over high-pressure tactics. We are here to simplify the variables and help you drive home in a vehicle you love with a payment plan that fits your lifestyle perfectly.
Ready to see your options? Browse Our Inventory and Get Pre-Approved in Fullerton Today. We look forward to welcoming you to our showroom and helping you find your next reliable ride with total ease.
Frequently Asked Questions
Can I get used car financing with a low credit score in Fullerton?
Yes, you can secure financing even with a lower credit score. Many local lenders in Orange County specialize in subprime or near-prime loans. While interest rates for scores below 600 can be higher, often reaching 19 percent or more, a solid down payment helps improve your chances. We act as a guide to help you find a manageable path forward, focusing on stability and your long-term relationship with the community.
What is a good interest rate for a used car in 2026?
A "good" rate depends entirely on your credit tier. For buyers in the super prime category, a competitive APR is around 6.29 percent. If your score is closer to the national average, you might see rates near 11.19 percent. It is helpful to remember that used car rates are higher than new car rates because collateral value is harder to appraise. We aim for transparency so you know exactly where you stand.
How long are typical used car loan terms?
Most used car loans in 2026 average around 68 months. While 72-month terms are available to keep monthly payments lower, they often result in paying more interest over time. We frequently recommend a 48-month or 60-month term for vehicles like a Toyota RAV4. This steady pacing helps you build equity faster and ensures you aren't "underwater" on the loan if you decide to trade in your vehicle later.
Do I need a down payment for a used Tesla Model 3?
You aren't always required to have a down payment, but we strongly suggest putting at least 10 to 20 percent down on a Tesla Model 3. This reduces the total amount you need to borrow and lowers your monthly obligation. Since California doesn't offer a trade-in tax credit, a cash down payment is the most effective way to lower the principal. It creates an immediate safety net for your investment in high-demand electric vehicles.
How does my trade-in affect my car loan application?
Your trade-in acts as a cash equivalent that directly reduces your loan principal. If you're wondering how does used car financing work with a trade-in, it essentially lowers your loan-to-value ratio. This makes you a more attractive candidate to lenders in Fullerton and Anaheim. By using the equity from your current Toyota or Honda, you can often qualify for better interest rates and significantly lower your total monthly commitment.
Is it better to finance through a bank or a dealership?
Both options have benefits. Banks and Orange County credit unions provide a great baseline, but dealership financing offers the convenience of "one-stop" shopping. We work with a broad network of regional lenders to find terms that fit your specific needs. This collaborative approach often uncovers specialized programs for high-demand models like the Toyota Prius that you might not find by applying to a single bank on your own.
What documents do I need to bring to Auto Sale Newport for financing?
To keep the process smooth and easy, please bring a valid driver's license, your two most recent pay stubs, and a utility bill to prove residency in Orange County. If you are trading in a vehicle, bring the title or current registration. Having these items ready allows us to explain how does used car financing work for your specific situation and get you behind the wheel of a Tesla Model Y much faster.
Can I pay off my used car loan early without penalties?
Most modern auto loans in California are simple-interest contracts, which means you can pay them off early without a penalty. Paying extra toward your principal each month is a smart way to reduce the total interest you pay over the life of the loan. We always encourage you to review the specific terms of your retail installment contract during our transparent signing process to ensure there are no surprises or hidden fees.


