
The lowest monthly payment can lead to the highest total repayment. When comparing used Tesla financing options California buyers can access, look at APR, loan term, down payment, and total payments together. A longer term may reduce the scheduled payment, but it can increase what you pay over the life of the loan.
It can be hard to know whether to start with dealership-arranged financing or get an offer from a bank or credit union. Approval, a trade-in, and California tax, title, and registration costs can all affect the final figures. Compare written offers using the same vehicle price and down payment to make a fair comparison.
This guide covers common financing routes, what to check in each offer, and how a trade-in and transaction costs may affect the numbers. It also explains which vehicle and loan details to review before signing, so you can ask informed questions and choose terms that fit your budget.
Key Takeaways
- Compare dealership-arranged financing, banks, credit unions, and paying cash to see which route fits your plans.
- Use written lender disclosures to review APR, amount financed, and total payments over the loan term.
- Compare used Tesla financing options California lenders offer using consistent assumptions, including the same vehicle price and down payment.
- Ask each lender which documents it requires, then review the vehicle and loan details before signing.
- If you’re shopping in Fullerton, you can ask about dealership financing and a trade-in valuation while weighing your options.
Used Tesla financing options in California: start with your buying plan
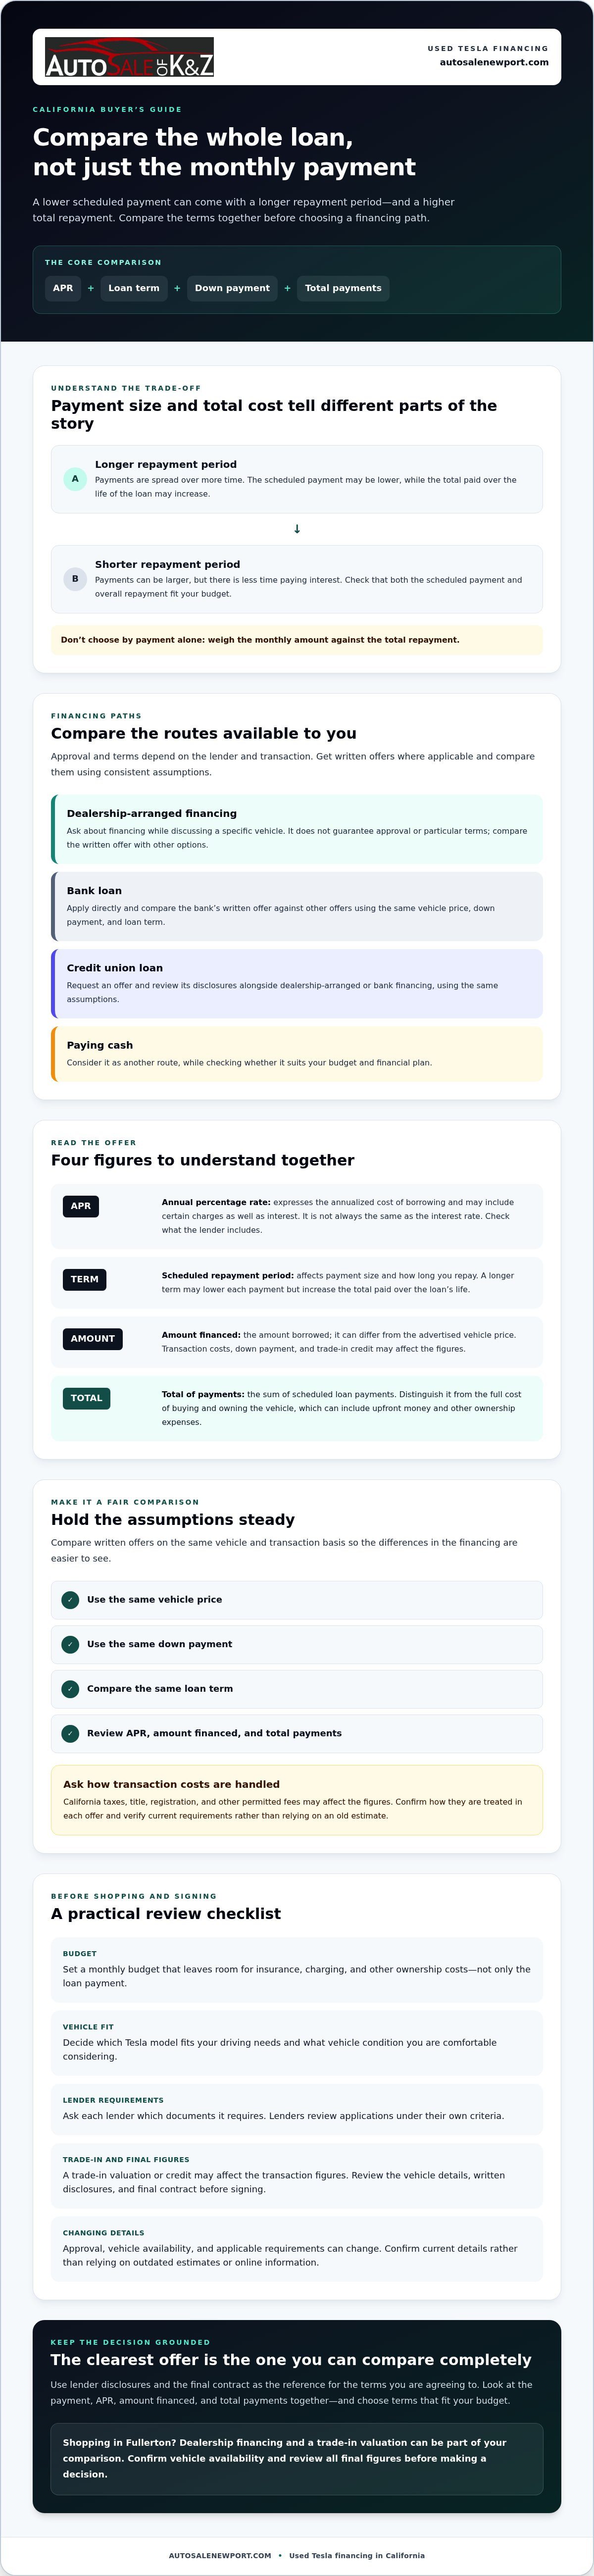
Compare the complete loan terms, not just the monthly payment. A lower payment may reflect a longer repayment period, so weigh the overall amount you’ll repay against what you can comfortably pay each month. Common routes to compare include dealership-arranged financing, loans from banks or credit unions, and paying cash.
With used Tesla financing options California buyers consider, approval, APR, loan length, and any required down payment depend on the lender and transaction details. Vehicle availability can change as well. Ask for written disclosures, and confirm how applicable California taxes, title, and registration costs are handled. Verify current requirements instead of relying on an old estimate or online information.
If you’re also considering possible incentives, check current program rules and eligibility. For background, see this overview of government incentives for electric vehicles.
For a practical overview of used-Tesla shopping, watch this video:
Which used Tesla financing routes can California buyers consider?
Dealership-arranged financing lets you ask about financing while discussing a specific vehicle, but it does not guarantee approval or particular terms. You can also apply directly with a bank or credit union, then compare its written offer with any dealership-arranged offer. Use the same vehicle price, down payment, and loan term for each comparison. Paying cash is another option to consider, though it may not suit every budget or financial plan.
What should you decide before shopping for a used Tesla?
Set a monthly budget that leaves room for insurance, charging, and other ownership costs, not just the loan payment. Then decide which Tesla model fits your driving needs and what vehicle condition you’re comfortable considering. These choices help you focus on vehicles and financing terms that suit your plans.
If you’re considering a Model 3, the used Tesla Model 3 buyer’s guide can help you prepare for your search. Auto Sale Newport in Fullerton offers financing options and trade-in valuations. Check current listings and confirm vehicle availability before visiting.
How used Tesla auto loans work: understand APR, term, and amount financed
A loan offer is more than a payment estimate. To compare used Tesla financing options California lenders may offer, look at how APR, the repayment period, and the amount financed work together. The lender’s written disclosures and final contract are the reference for the terms you’re agreeing to. The Consumer Financial Protection Bureau also offers guidance on understanding your auto loan options.
What do APR, loan term, and amount financed mean?
APR, or annual percentage rate, expresses the annualized cost of borrowing and may include certain charges as well as interest. It is not always the same as the interest rate. Check the lender’s disclosures to see what the APR includes, and compare offers based on the same assumptions.
Loan term is the scheduled period for repaying the loan. A longer term spreads payments over more time, which can lower each payment but may increase the total paid over the life of the loan. A shorter term can mean larger payments but less time paying interest. Check that both the scheduled payment and overall repayment fit your budget.
Amount financed is the amount borrowed, which can differ from the vehicle’s advertised price. Depending on the transaction, taxes, title or registration charges, other permitted fees, a down payment, or a trade-in credit may affect the figures. The total of payments is the sum of scheduled loan payments. Review both figures, and distinguish them from the full cost of buying the vehicle, which may include money paid upfront and other ownership expenses.
How can credit and vehicle details affect a loan offer?
Lenders review each application under their own criteria. Credit history and other application information can affect the offered APR, loan amount, or approval decision. No credit score by itself guarantees approval. A co-applicant or down payment may affect how a lender considers an application, subject to its approval.
The vehicle matters, too. Age, mileage, and condition may affect whether a lender will finance a particular used Tesla and on what terms. Ask about the lender’s vehicle eligibility rules before relying on an estimate. When comparing an offer arranged through a dealership with one from a bank or credit union, use the same vehicle, down payment, and term assumptions, then review the written disclosures side by side.
For a specific pre-owned Tesla, you can review available vehicles and ask about financing options before deciding. Confirm current inventory and financing terms directly.
Compare California used Tesla financing offers beyond the monthly payment
A useful comparison puts each offer on equal footing. When reviewing the used Tesla financing options California lenders or dealerships present, use the same vehicle price, down payment, and loan assumptions wherever possible. A smaller payment may reflect a longer term, a different amount financed, or costs handled differently. Compare the written terms before deciding.
| Lender or offer | APR | Term | Amount financed | Fees and optional items | Total of payments |
|---|---|---|---|---|---|
| Offer A | Record from disclosure | Record from disclosure | Record from disclosure | List and verify | Record from disclosure |
| Offer B | Record from disclosure | Record from disclosure | Record from disclosure | List and verify | Record from disclosure |
What should you compare on every written financing offer?
Check the APR, scheduled term and payment, amount financed, and total of payments. Review fees, add-ons, optional products, and any cancellation terms in the paperwork. Ask whether an offer applies to the specific used Tesla you’re considering, because lender criteria and transaction details can differ. If offers use different assumptions, request revised written figures before comparing them.
Don’t choose based on payment alone. Extending the term can lower the scheduled monthly amount while changing the total repayment. Consider both figures, and make sure the amount financed matches the transaction documents.
How do trade-ins and California transaction costs fit in?
Ask how the trade-in valuation is determined and how any agreed value appears in the transaction paperwork. Separate the vehicle price, taxes, title and registration costs, and optional items so you can see what each amount represents. California taxes and government-related charges can vary with transaction and location details. Verify current figures and requirements with the relevant authority, and review the written disclosures before signing.
Eligible buyers may also want to check current requirements for California's clean vehicle financing programs. Confirm directly with the program whether it applies to your circumstances and the vehicle you’re considering. Don’t assume assistance will be available or included in a lender’s offer.
For checks beyond financing, see the used electric vehicle buying guide. A side-by-side comparison helps you understand each offer on its own terms instead of letting one appealing monthly payment make the decision for you.
Prepare for used Tesla financing in California with a step-by-step checklist
Preparing in advance can make financing discussions clearer and help you catch missing details before signing. Use this checklist to organize your budget, lender questions, vehicle checks, and paperwork. Requirements vary, so confirm specifics with each lender and verify current California transaction details with appropriate sources.
- Set your budget. Decide what monthly payment fits alongside insurance, charging, and other ownership costs. Leave room for taxes, title, and registration expenses, and don’t base your decision on the loan payment alone.
- Research lenders. Ask banks, credit unions, and any dealership financing contact what options may fit the vehicle and your circumstances. For the used Tesla financing options California buyers compare, request written terms rather than relying only on an estimate.
- Ask which documents are required. Each lender may have its own application process. Ask whether it needs identity, income, residence, insurance, or vehicle documents. Also ask whether submitting an application involves a credit inquiry and how that inquiry is handled.
- Review the specific Tesla. Check the vehicle identification number (VIN), history, title information, available service records, condition, mileage, and any battery information provided. Arrange a test drive and consider an independent evaluation where appropriate.
- Compare the final paperwork. Confirm that the written financing offer matches the selected vehicle and transaction. Review disclosures, fees, taxes, title and registration details, and optional items before agreeing to the terms.
What documents and questions should you prepare?
Don’t assume every lender requires the same paperwork. Ask for its document list before applying, and keep your questions together. Along with APR, term, and fees, ask how payments are made, what the payoff process involves, and whether any prepayment conditions apply. If a term is unclear, ask for an explanation in writing.
What should you check on a used Tesla before financing?
Match the VIN on the vehicle and purchase documents to the VIN named in the loan offer. Review the records and vehicle details available to you, and ask about anything missing or unclear. A test drive can help you decide whether the vehicle suits your needs, while an independent evaluation may offer another perspective. Neither replaces checking the written transaction and financing terms.
Before signing, verify applicable California tax, title, registration, and consumer-disclosure details with the relevant agencies. Review how they appear in the paperwork. If you’re considering a Tesla in Fullerton, review available used Tesla inventory and ask about financing or a trade-in valuation. Confirm vehicle availability and any financing requirements before making plans.
Choose a used Tesla financing path and take the next step in Fullerton
Your next step depends on what you’ve learned from comparing offers. If you want to see how bank or credit union terms compare, get and review those written details before focusing on a specific vehicle. If you’re still weighing your options, ask about dealership-arranged financing while considering a particular Tesla. Neither route guarantees approval or better terms. Compare the actual disclosures and take time to decide.
When might dealership-arranged financing be worth discussing?
It can be convenient to ask about financing while reviewing a specific used Tesla, especially if you want to understand the purchase and financing details together. Ask which lenders and terms apply to your application, what information is required, and whether the written offer is tied to that vehicle and transaction. Confirm current details directly, then compare the offer with any outside lender’s terms. You can ask questions and review the figures without agreeing to accept an offer immediately.
What are the next steps for Fullerton-area Tesla shoppers?
Auto Sale Newport is an independent used-car dealership in Fullerton with Tesla Model 3 and Model Y inventory, financing options, and trade-in valuations. Start by checking current listings and confirm the vehicle you’re considering is still available before visiting. If you have a trade-in, ask how its value is assessed and what information to bring for an appraisal. You can also ask which financing steps apply and what documents to have ready.
For shoppers comparing a Tesla from Fullerton, Orange County, Los Angeles, Riverside, Long Beach, Bakersfield, San Bernardino, Corona, San Diego, Anaheim, Buena Park, Santa Ana, or Orange, the same approach applies: check current vehicle availability and compare written financing terms before making a decision. Auto Sale Newport’s showroom is at 1565 W Commonwealth Ave in Fullerton. If you want to see a specific Tesla in person, ask about arranging a test drive and confirm availability first. Reviewing a vehicle and discussing financing are practical next steps, not a commitment to proceed.
To continue your search, explore Auto Sale Newport’s current inventory. Compare the used Tesla financing options California buyers may consider alongside the specific vehicle and written loan terms. Take the time you need to ask questions and make an informed decision.
Move forward with clear numbers and the right vehicle
A sound financing decision starts with comparing written terms, not just the monthly payment. Review APR, loan length, amount financed, and total payments side by side, then confirm that the vehicle and California transaction details match the offer. This makes it easier to assess used Tesla financing options California buyers may consider without rushing.
Auto Sale Newport is a Fullerton used-car dealership offering financing options, trade-in valuations, and on-site appraisals. Tesla Model 3 and Model Y are among its offerings, though inventory can change. If you’re considering a trade-in, ask how its valuation fits into the transaction, and confirm vehicle availability before planning a visit or test drive.
Browse available used Teslas and ask Auto Sale Newport about financing options, or bring your questions to the showroom at 1565 W Commonwealth Ave in Fullerton. Review your choices at your own pace and choose the vehicle and terms that fit your plans.
Frequently Asked Questions
Can you finance a used Tesla in California?
Yes. Used Teslas can be financed in California, subject to lender approval and vehicle eligibility rules. Banks, credit unions, and dealership-arranged financing may be options to explore. Approval, APR, loan length, and down payment depend on your application, lender, vehicle, and transaction. Before committing, review the written loan disclosures and confirm how taxes, title, and registration costs are shown.
What used Tesla financing options are available in California?
Common routes include applying directly with a bank or credit union, asking a dealership about financing options, or paying cash. To compare used Tesla financing options California buyers may consider, request written terms and use the same vehicle price, down payment, and loan assumptions. Paying cash avoids an auto loan but may not fit every budget. Confirm lender requirements and vehicle eligibility directly.
How does dealership-arranged financing compare with a bank or credit union loan?
Dealership-arranged financing lets you ask about financing while discussing a specific vehicle. A bank or credit union application gives you a separate offer to compare. Neither route is automatically cheaper, faster, or more likely to result in approval. Ask which lenders and terms apply to your application, then compare written APR, term, amount financed, fees, and total payments using consistent assumptions.
How much down payment do you need to finance a used Tesla?
There is no single down payment that applies to every used Tesla loan. The amount, if required, depends on lender criteria, your application, the vehicle, and the transaction. Ask each lender about its down-payment requirements and how the amount affects the balance financed and scheduled payments. Compare offers using the same down payment, and make sure your budget accounts for taxes, registration, insurance, and ownership costs.
Does a used Tesla’s age or mileage affect financing approval?
It can. Lenders may set eligibility rules based on a vehicle’s age, mileage, condition, or other details, and those policies differ. Ask whether the specific Tesla you’re considering qualifies before relying on an estimate. Also review the vehicle’s history, title information, condition, and available records. Approval depends on the full application and lender criteria, so no single vehicle detail guarantees a particular decision.
Can I use a trade-in toward a used Tesla purchase in California?
Yes. A trade-in may be part of the purchase transaction, but its value and effect on the amount you need to finance depend on the agreed valuation and transaction details. Ask how the valuation is determined and how it appears in the paperwork. If there is an existing loan on your trade-in, ask how any remaining balance will be handled. Auto Sale Newport offers trade-in valuations in Fullerton.
What should I compare besides the monthly payment on a used Tesla loan?
Compare APR, loan term, amount financed, fees, scheduled payments, and total payments. Check for optional products and review their terms before signing. A longer loan term can reduce the monthly payment while changing the total repayment, so consider both figures. Keep the vehicle price, down payment, and loan assumptions consistent across offers, and verify that each written offer matches the Tesla and transaction you’re considering.


